Risk-On Sentiment Fades as Heavy Earnings Week Begins
The week in financial markets begins with a sharp slowdown in risk-on sentiment. The technology sector remains volatile as investors await next Wednesday’s first major batch of earnings reports, with Tesla, IBM and Meta due to report. Meanwhile, the complex situation in the Middle East continues to loom large, with fresh threats of escalation and oil prices still significantly elevated. Gold is recovering as the rise in bond yields loses momentum and expectations grow that the Fed will remain on hold in October. Overall, our Health Scores point to a neutral market environment, while volatility is edging slightly higher. Futures indicate a flat opening for European markets and a positive start for the US.
Market Weather Map
October 19, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
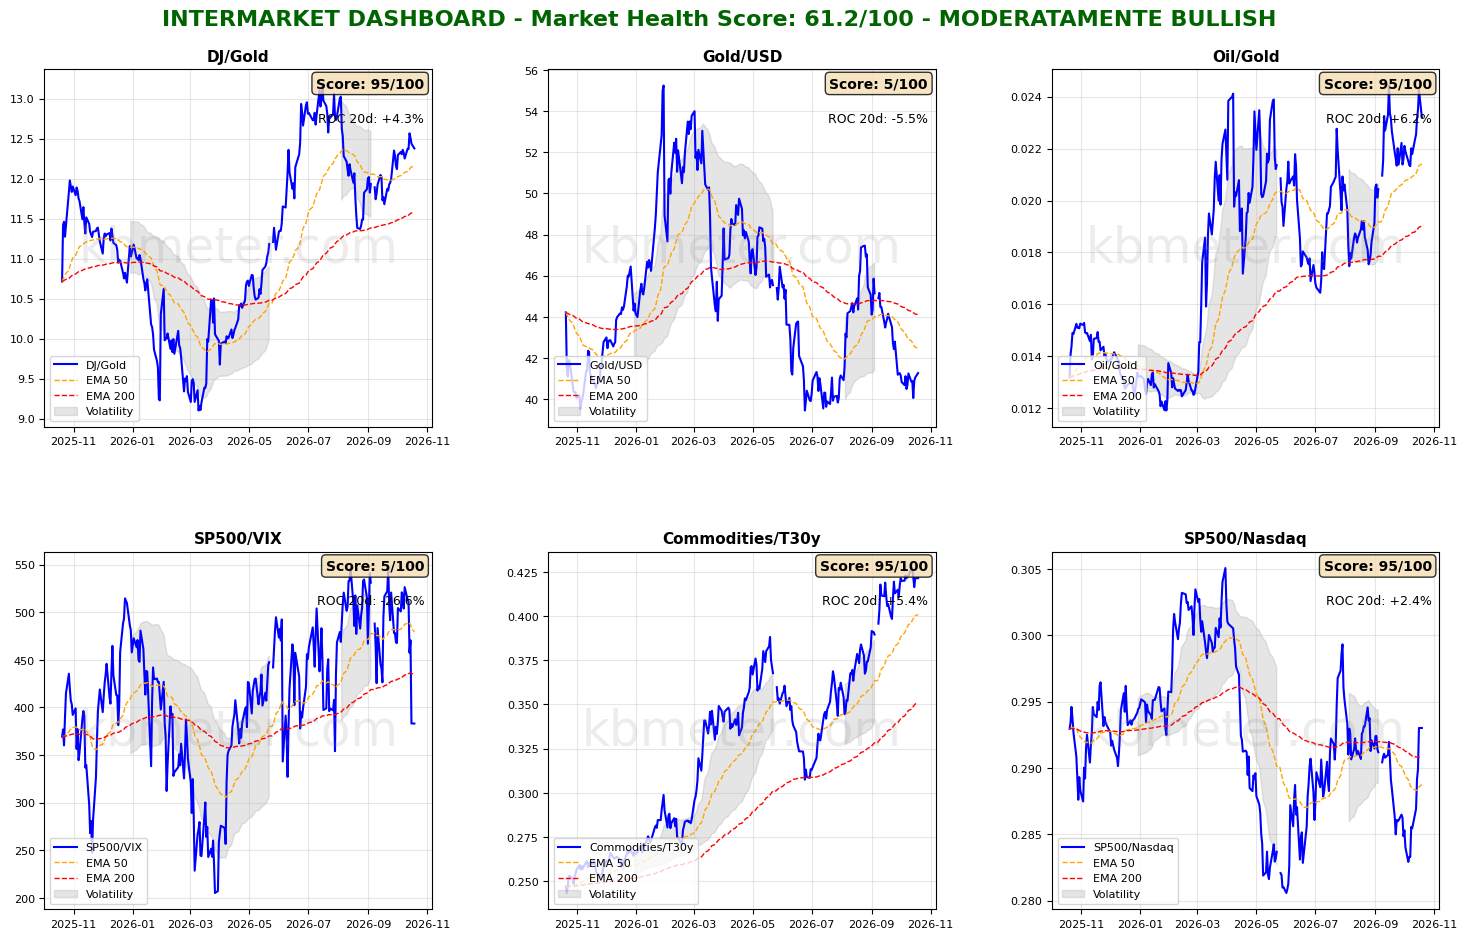
Financial markets are showing neutral sentiment today. Our intermarket analysis points to a Market Health Score of 61/100.
The week opens with two signals that are not particularly supportive of risk-on sentiment. Our intermarket dashboards show the S&P 500/VIX ratio falling below its long-term moving average, while the S&P 500/Nasdaq ratio breaks above its long-term moving average and climbs to its highest level since late August. Expectations that the Fed will remain on hold in October, together with a recovery in the bond market, are providing support for gold, which is posting modest gains against both the US dollar and oil. The overall picture nevertheless remains inflationary, with the Commodities/Bonds ratio firmly at its period highs.
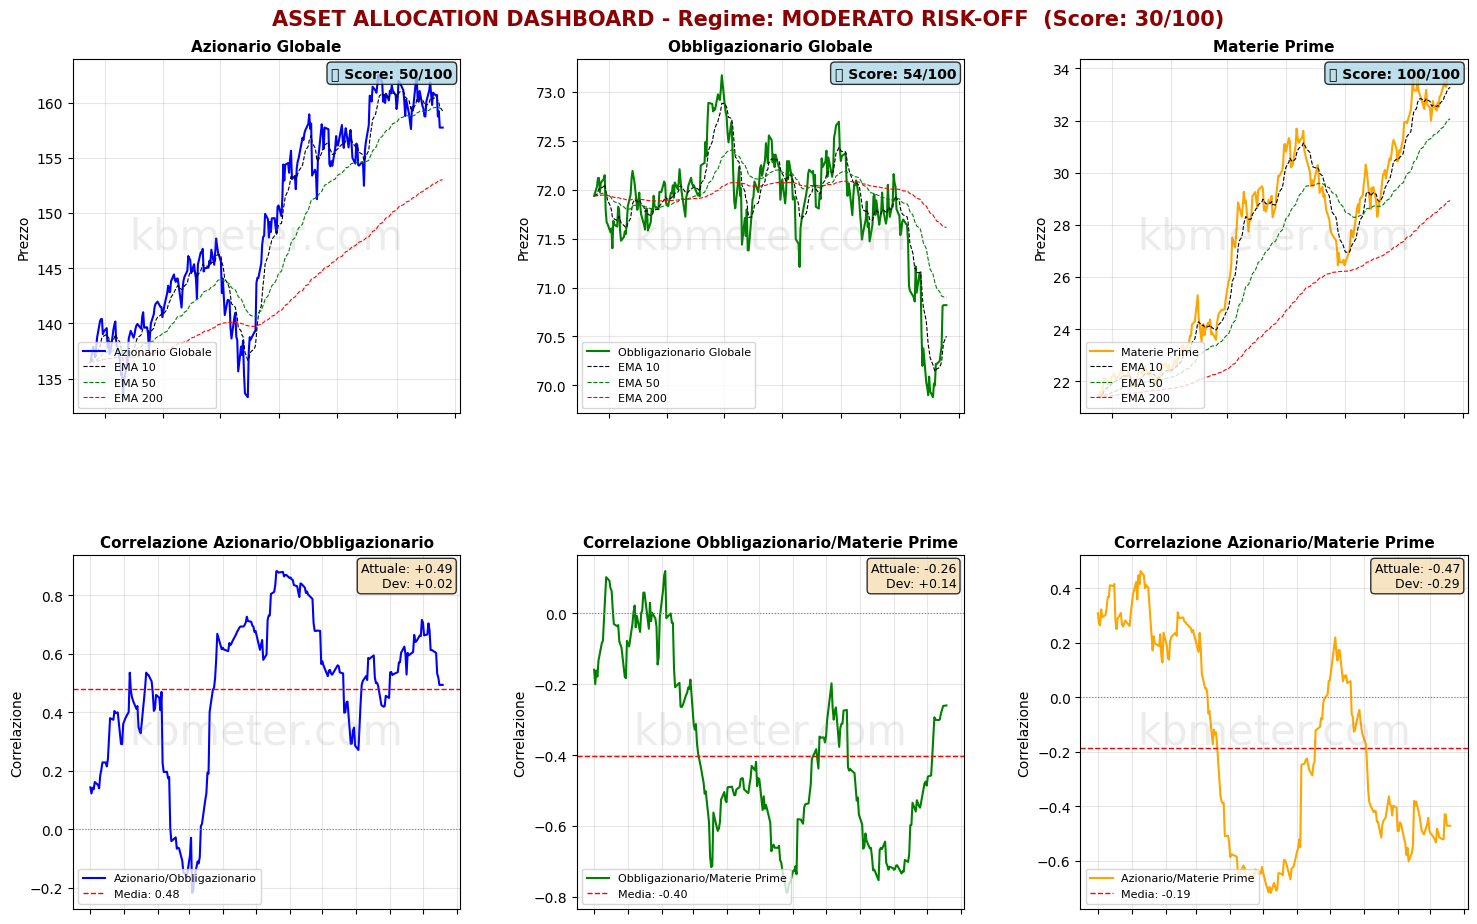
Looking at the various asset classes, the starting lineup for the week suggests that global bonds are attempting to target their medium-term moving average. This would represent the first concrete test of a potential rebound. Equities, meanwhile, remain range-bound as investors await the week’s major earnings releases. Commodities continue to trend higher. Notably, the correlation between equities and bonds is moving back towards its annual average. It remains in positive territory, although the strength of the correlation is weakening.
Our market weather map confirms a broadly neutral environment. The global average Health Score across the monitored assets has risen to 51. None of the major asset classes has reached a score of 60. We are seeing a recovery in gold alongside a slight weakening of the US dollar, while equity markets remain more volatile in Asia. Europe has overtaken North America in terms of average Health Score.
As for seven-day changes, two figures stand out. The VIX has surged by nearly 22 points over the past week, while, at the other end of the spectrum, the Growth style has lost almost 17 points. Momentum in the energy sector is also strengthening, reflecting renewed uncertainty surrounding developments in the Middle East.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures point to a moderately risk-on sentiment (+0.20% on average), with US markets in positive territory (+0.89%), Europe slightly lower (-0.12%) and Asia modestly higher (+0.47%).
📊 Global Futures – Pre-Market Sentiment
- Nikkei 225: +2.13%
- US Tech 100: +1.34%
- Russell 2000: +0.85%
- Taiwan: -0.99%
- Hang Seng: -0.71%
- CAC 40: -0.57%
Macroeconomic calendar
On the macroeconomic front, the week kicks off with Chinese economic data and Canada’s September 2026 inflation figures.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 19 October 2026 - 7:55 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.