Markets Stay Neutral-to-Moderately Positive as Equities-Yields Dynamic Holds Firm
Financial markets continue to grapple with two deeply divergent narratives across equities and fixed income. Sentiment remains between neutral and moderately positive, with equities still in neutral territory according to our scores, although elements of risk-on behavior are emerging from the intermarket analysis. Fixed income remains at its lows for the period, with yields still moving higher, weighing on precious metals, while interest-rate expectations are keeping the dollar above 60 on our score. Attention is shifting toward Europe, which is dealing with inflation, rising government bond yields, and political deadlines. French equities have lost 10 points on our score over the past seven days, while the Euro/Dollar exchange rate has shed almost 20 points from its late-August peak. Futures point to a positive opening for both European and US markets.
Market Weather Map
October 6, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
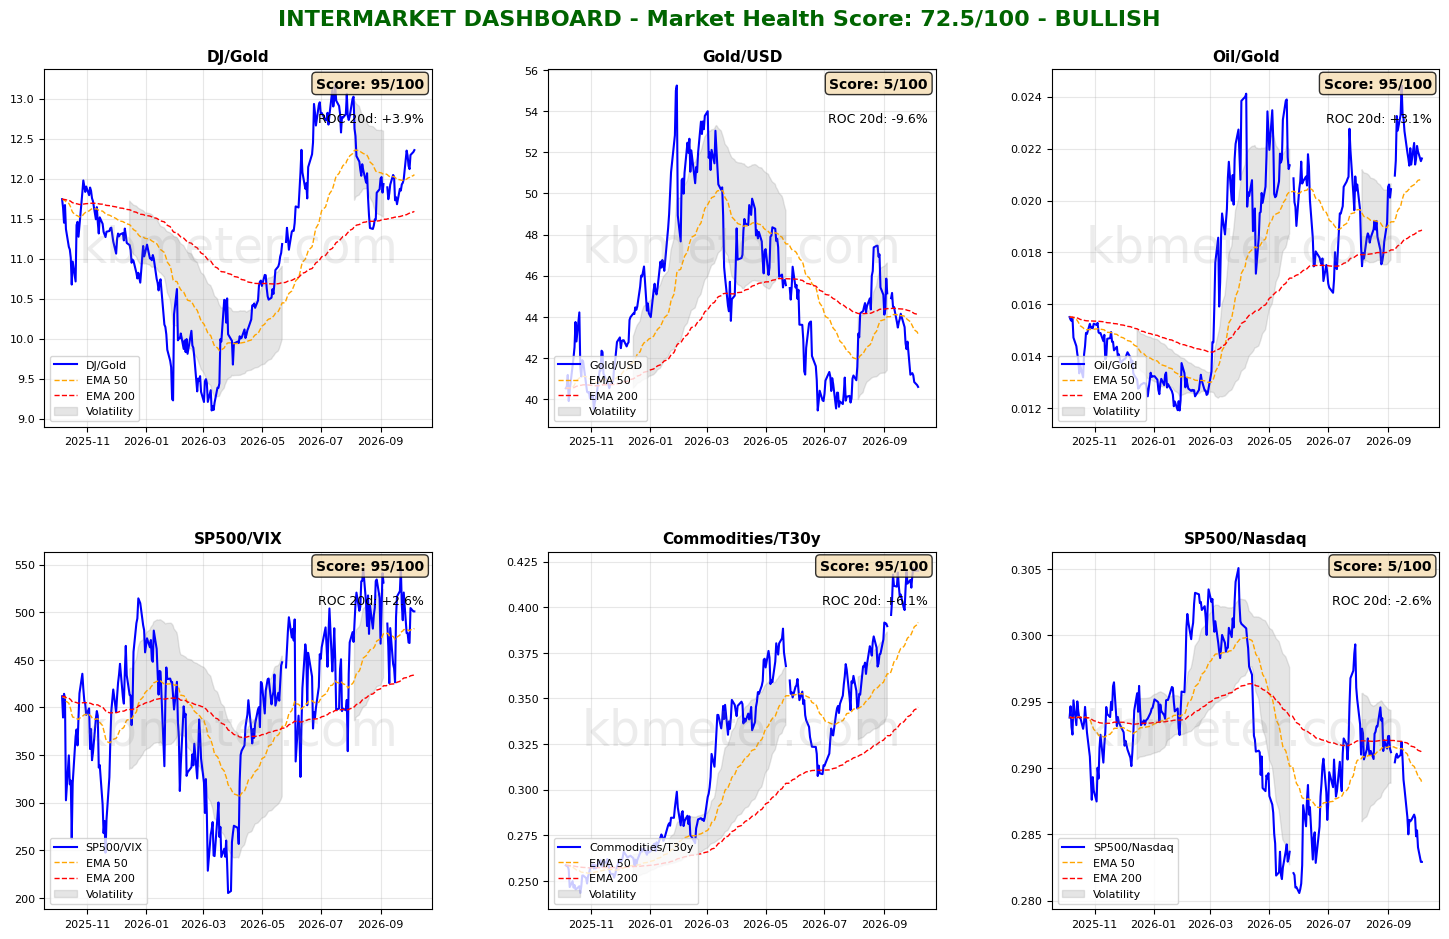
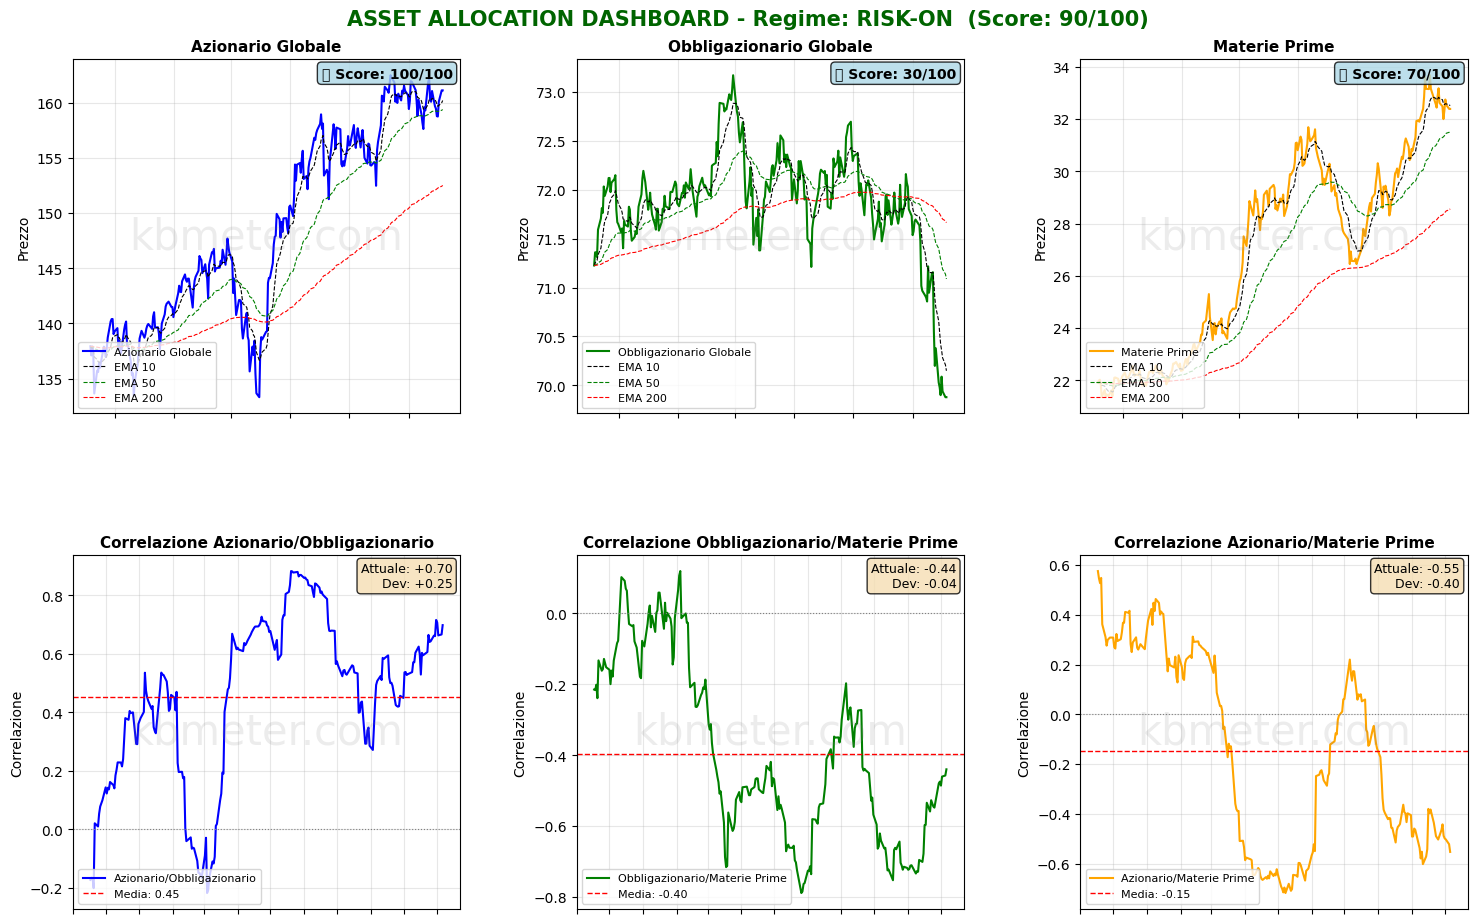
Financial markets are showing neutral/moderately positive sentiment today. The intermarket analysis points to a Market Health Score of 72/100. Our intermarket dashboards continue to tell a two-sided story. It is still too early to say whether this represents the new normal, and for now we can only describe what we are observing. Sentiment toward equities remains in positive territory, with both the Dow/Gold ratio and the S&P 500/VIX ratio moving higher. Oil is stabilizing and maintaining some relative strength versus gold, while the dollar remains strong. Technology is strengthening further, with the S&P 500/Nasdaq ratio returning to levels last seen in June, very close to the lows of the period. The other side of the story concerns bond yields, which continue to trend higher. The Commodities/Bonds ratio has reached a new period high, driven primarily by weakness in the denominator.
The asset classes tell the same story from a different perspective. Global fixed income remains at its lows for the period and does not appear to have enough strength to rebound from its current levels. Global equities are oscillating around their short- and medium-term moving averages, while maintaining a bullish bias. Commodities remain stable near their period highs.
Our market weather map has not changed significantly compared with the latest analyses. The neutral zone for equities is confirmed, with technology still trading at higher valuations than US equities overall, although the gap has narrowed. Gold remains in negative territory and the dollar in positive territory, while oil has moved back into an almost perfectly neutral zone.
Looking across all the assets we monitor, the notably negative score for US dollar-denominated High Yield stands out, both in the short and long term. On the equity side, on a monthly basis, two figures stand out: the +18 score for Brazilian equities and the -10 score for French equities, reflecting the markets’ divergent expectations regarding the current situation in the two countries.
Finally, we cannot overlook the Euro/Dollar exchange rate, which has fallen to a score of 37, losing almost 20 points from the peak reached in late August. This signals a rapid repositioning in response to the delicate phase currently facing the euro area economy.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures point to a moderately risk-on sentiment (+0.28% on average), with the US slightly positive (+0.11%), Europe slightly positive (+0.45%), and Asia slightly positive (+0.24%).
📊 Global Futures – Pre-Market Sentiment
- IBEX 35: +0.99%
- FTSE MIB: +0.81%
- Nikkei 225: +0.71%
- Hang Seng: -0.26%
- Taiwan: -0.11%
- CAC 40: +0.00%
Macroeconomic calendar
Today’s macroeconomic calendar includes German factory orders for August, Spanish and French industrial production for August 2026, August retail sales in the Euro area, the latest September construction PMI surveys, and August exports from the US and Canada.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 6 October 2026 - 8:31 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.