Markets End Week in Neutral Territory as Earnings Loom; Bonds Attempt to Bottom
Financial markets are heading into the close of a week once again dominated by bond yield dynamics and the ongoing debate surrounding AI. Yesterday, the flurry of reports about OpenAI’s revenue figures sent shockwaves through the technology and semiconductor sectors. The turmoil has since subsided, but it is a clear sign of the tension building ahead of the next round of quarterly earnings reports. On the bond market front, the successful outcome of yesterday’s US Treasury auction and the global bond index’s return above its short-term moving average suggest that a bottoming process may already be underway — a view that should be treated with extreme caution. These early signs, together with a slight decline in oil prices, underpin gold’s modest recovery. However, gold remains weak according to our scores and will need to be monitored closely over the coming days. Market sentiment remains in neutral territory, while futures point to a slightly positive opening for both the US and European markets.
Market Weather Map
October 9, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
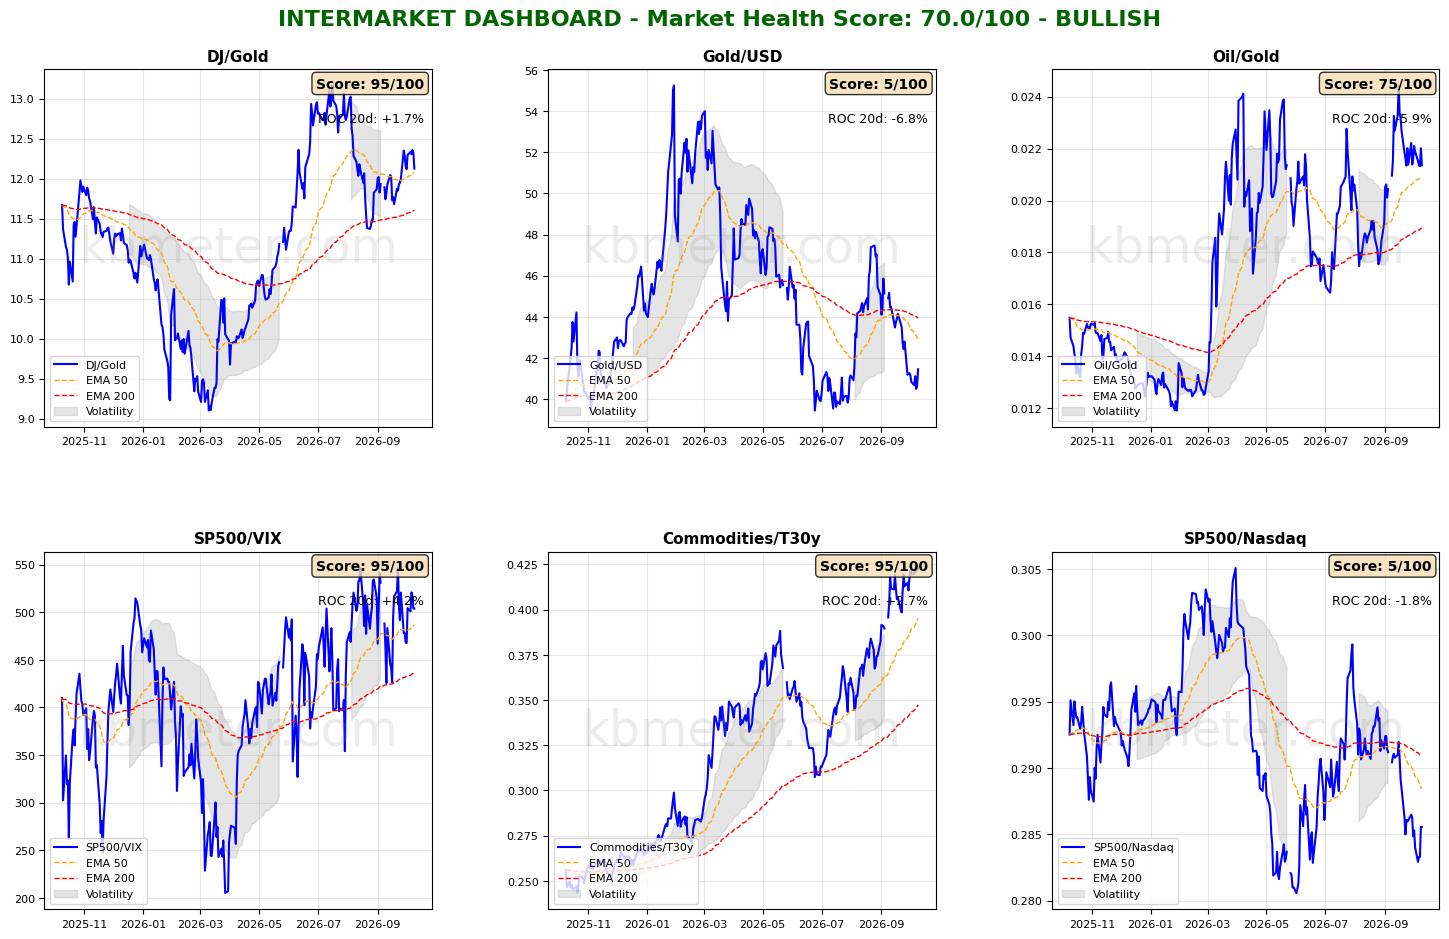
Financial markets are currently showing neutral sentiment. Our intermarket analysis reports a Market Health Score of 70/100. There have been few changes across our intermarket dashboards, with the only notable development being gold’s recovery against both the Dow and the US dollar. This tentative strengthening, which remains to be confirmed, follows a particularly strong US Treasury auction, with yields edging lower. Risk appetite remains broadly stable, as does the Commodities-to-Bonds ratio, which continues to hover near its highs. Overall, this confirms the stabilisation phase we highlighted in previous analyses.
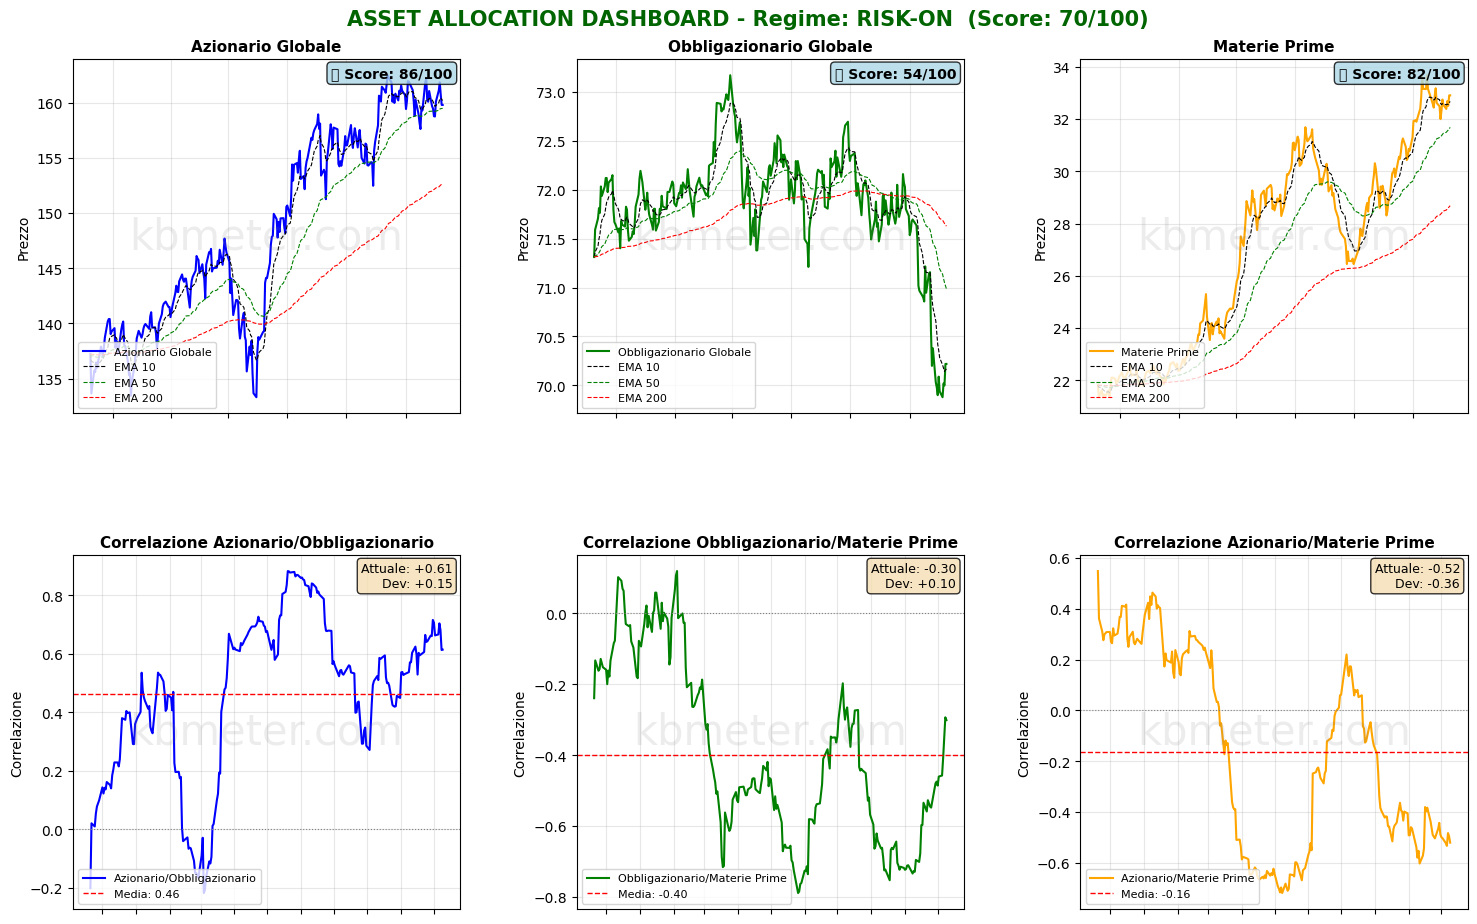
We continue to monitor developments in global fixed income. Yesterday, bond prices moved back above their short-term moving average, providing a small additional piece of evidence in support of the hypothesis that a bottom may have been reached. Nevertheless, considerable caution is still warranted. Equities remain broadly stable and largely range-bound, while commodities continue to balance opposing forces.
Our market weather map confirms the current picture. Equities remain in neutral territory, with the US market showing greater strength. Oil, commodities and cryptocurrencies are broadly neutral, while gold continues to show weakness. Fixed income has gained four score points compared with September and is approaching neutral territory. US 7–10-year Treasuries have gained nearly five score points in a single day.
Global Futures – Pre-Market Sentiment
Global futures point to a moderate risk-on sentiment (+0.21% on average), with the US slightly positive (+0.32%), Europe slightly positive (+0.20%) and Asia slightly positive (+0.21%).
📊 Global Futures – Pre-Market Sentiment
- Nifty 50: +1.12%
- Hang Seng: +1.02%
- Nikkei 225: +0.97%
- CSI 300: -1.35%
- Taiwan: -1.13%
- FTSE MIB: -0.61%
Macroeconomic calendar
Today’s macroeconomic agenda includes Italy’s industrial production data for August, Canada’s employment figures for September 2022, and the preliminary estimate of the University of Michigan’s US Consumer Sentiment Index.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 9 October 2026 - 8:33 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.