Markets Brace for Key Macro Data: Eurozone Inflation, US Jobs in Focus; Sentiment Neutral
The week draws to a close with important macroeconomic data releases, providing financial markets with another opportunity to assess the growth outlook and the prospects for monetary policy. On the one hand, there is inflation in the Eurozone and its political implications, with the debate over flexibility gaining momentum; on the other, there are the September US labour market figures. The direct implications of these data for the ECB’s and Fed’s policy decisions are clear. In particular, for the US central bank, a slowdown in the labour market would call for greater caution regarding any further rate hikes, while renewed price pressures in the Eurozone would accelerate the adoption of another rate increase by the ECB.
Pressure on yields remains high, equities remain in neutral territory, and oil continues to oscillate between hopes and new threats. Overall sentiment remains neutral, while futures point to a slightly positive opening for US markets and another negative start for Europe.
Market Weather Map
October 2, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
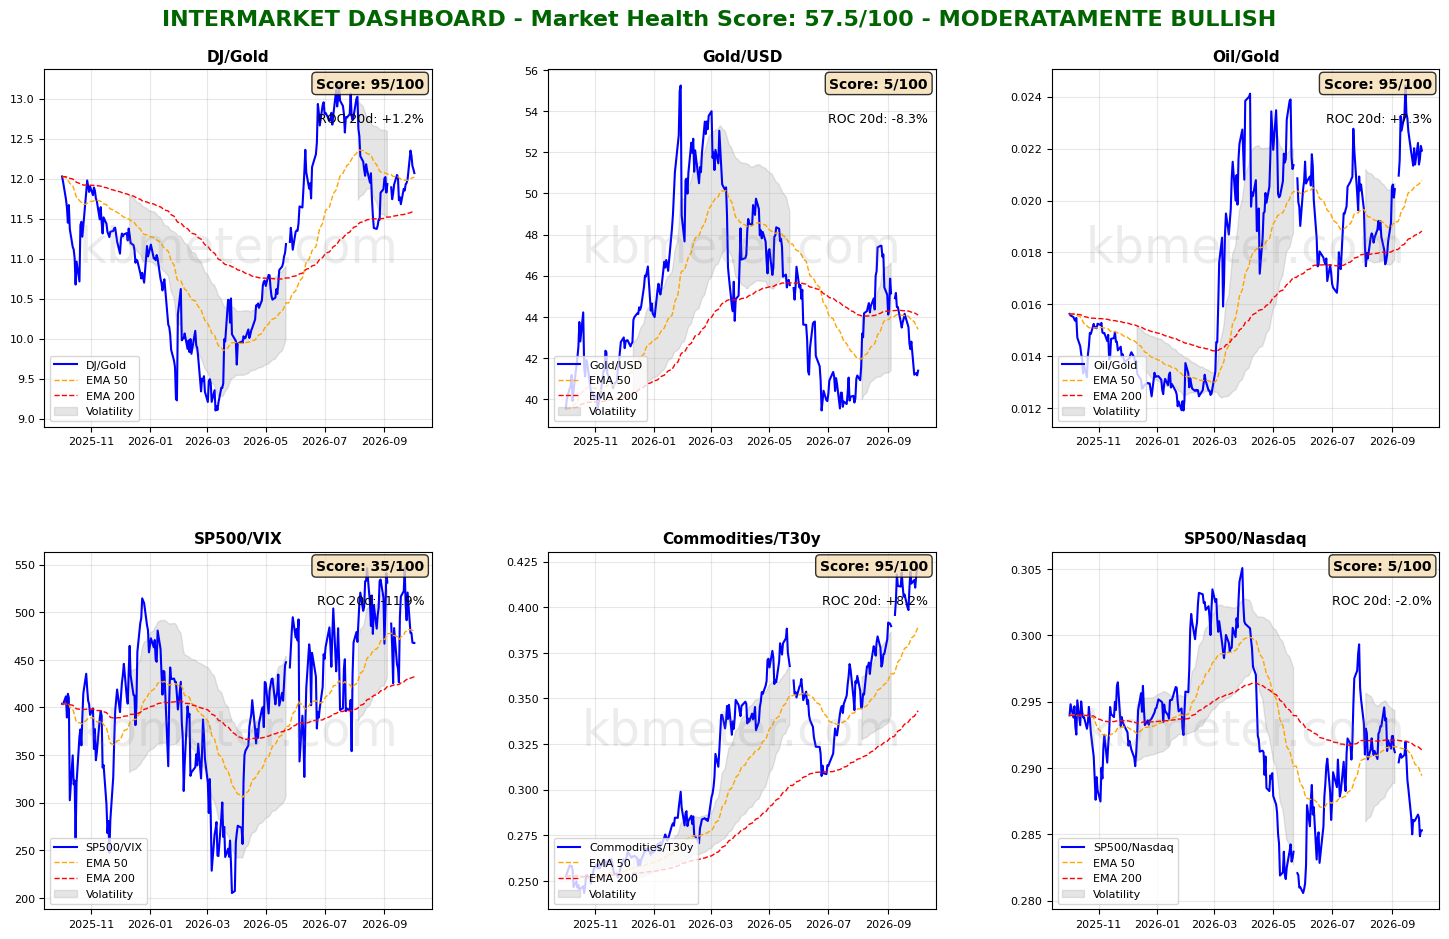
Financial markets are showing neutral sentiment today. Intermarket analysis indicates a Market Health Score of 58/100. Our intermarket dashboards confirm yesterday’s picture, with no significant shifts in risk appetite currently emerging. The Commodities/Bonds ratio has reached a new period high, while the S&P 500/VIX ratio remains slightly below its medium-term moving average. Gold has marginally strengthened relative to the Dow, while the ratios versus the Dollar and Oil remain broadly stable.
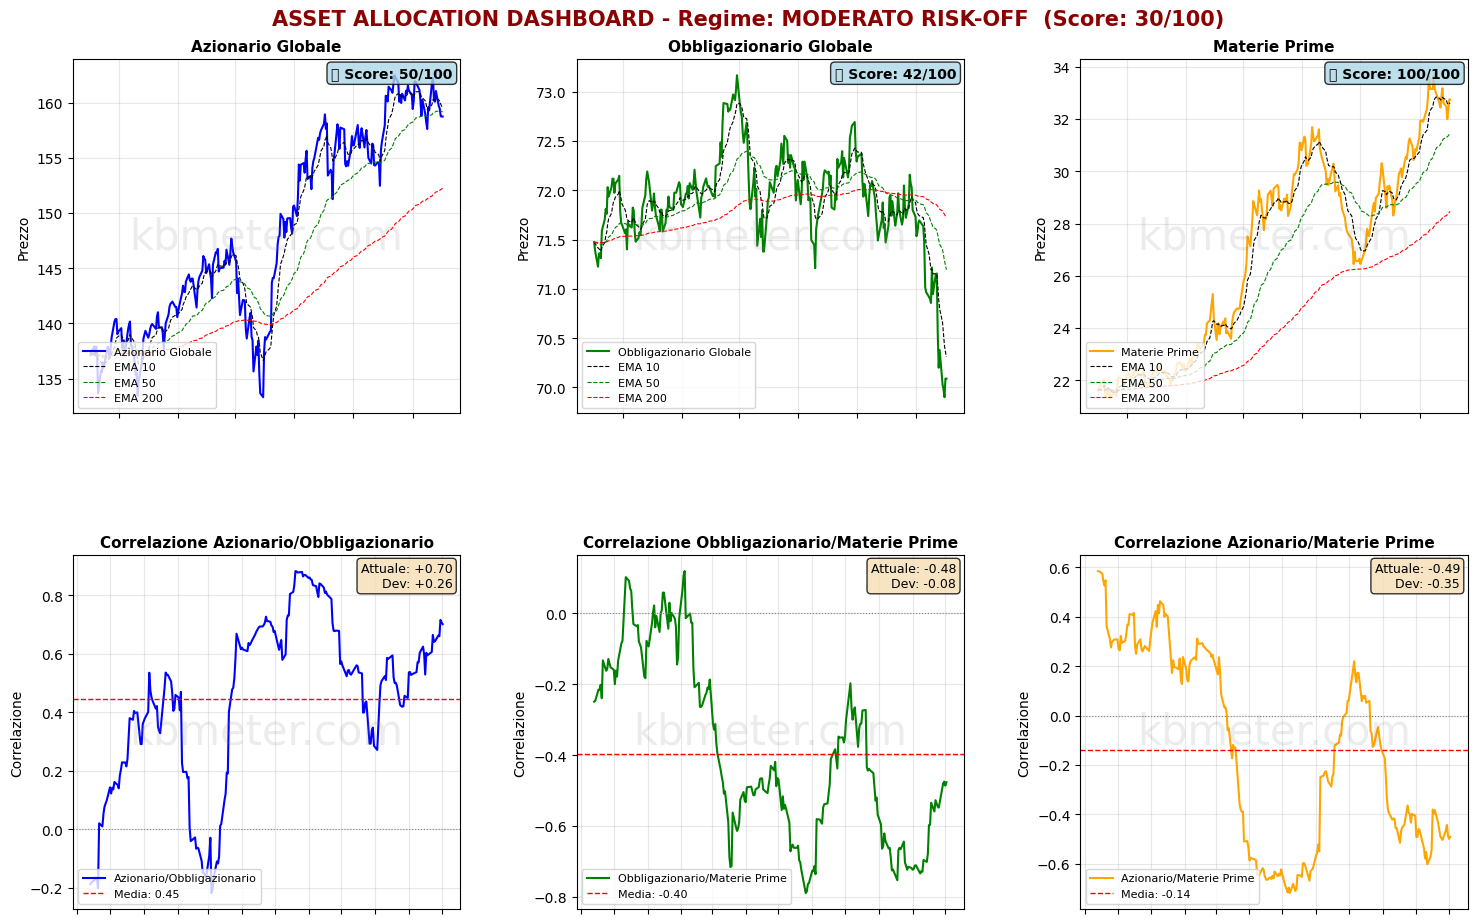
The asset-class chart is probably the most interesting one at the moment, as it provides a relatively noise-free view of how investors are positioning themselves. Global bonds remain near their lows and are attempting to stabilize, while equities remain slightly below their medium-term moving average. Commodities, despite higher volatility, remain biased to the upside. Under a normal scenario, and based on historical market literature, this could be interpreted as a late-expansion-cycle environment. However, it is important to remember that the current backdrop displays significant anomalies.
Our weather map confirms this picture. Equities are weakening but remain within neutral territory, while conditions remain stable for bonds, gold and oil. The dollar and crypto assets are showing a slight cooling trend. From a daily-change perspective, it is worth highlighting the increase of more than five points in the score of short-term US inflation-linked securities, which currently have a higher score than long-term TIPS.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures point to a moderately risk-off sentiment (-0.25% on average), with the US slightly positive (+0.38%), Europe negative (-0.50%), and Asia negative (-0.58%).
📊 Global Futures – Pre-Market Sentiment
- US Tech 100: +0.48%
- Russell 2000: +0.42%
- US 500: +0.33%
- Hang Seng: -2.04%
- IBEX 35: -1.99%
- FTSE MIB: -1.60%
Macroeconomic calendar
The macroeconomic agenda revolves around two highly anticipated releases. On the one hand, the September US labour market figures; on the other, September inflation data for the Eurozone. Also worth monitoring are US industrial orders for August and the Japanese labour market data.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 2 October 2026 - 8:22 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.