Markets Brace for Inflation Data, Micron Results and AI Focus
Financial markets are gearing up for a data-heavy macroeconomic session, while geopolitical uncertainties remain in the background and pressure on yields is beginning to show up in sovereign debt spreads as well (the BTP-Bund spread has moved back above 100 basis points, while the OAT-Bund spread is also widening).
The key word today will be inflation: inflation data from the three main Eurozone economies will be closely watched to assess the ECB’s next moves, while the US PCE price data will be key to reassessing the probability of another Fed rate hike between November and December (October remains unlikely unless the data come in significantly negative).
While the fixed-income market remains under pressure, moderate confidence continues to prevail in equities. Investors are trying to assess the implications of Trump’s meeting with leading figures from the tech industry, while awaiting Micron’s results, due out this evening. Overall, sentiment remains neutral, while futures point to a positive open for both European and US markets.
Market Weather Map
September 30, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
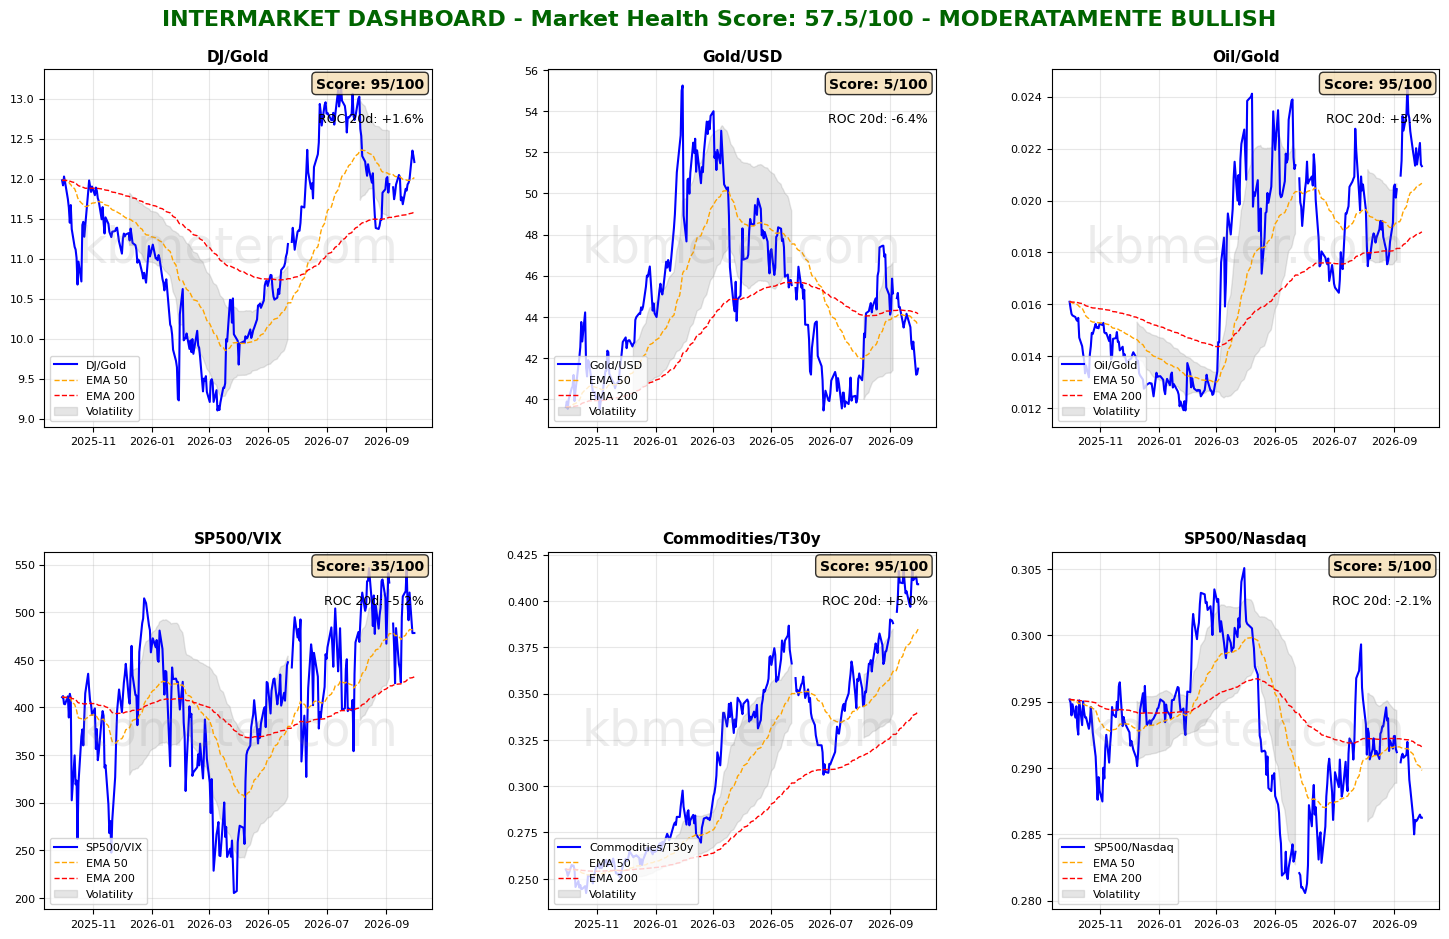
Financial markets are showing neutral sentiment today. The intermarket analysis points to a Market Health Score of 58/100. Yesterday was a day of consolidation across our intermarket dashboards. The overall scenario remains a combination of pressure on yields/inflation expectations and moderate risk-on sentiment in equities. Overall, therefore, neutral sentiment prevails, with the S&P 500-to-VIX ratio slipping slightly below its medium-term moving average.
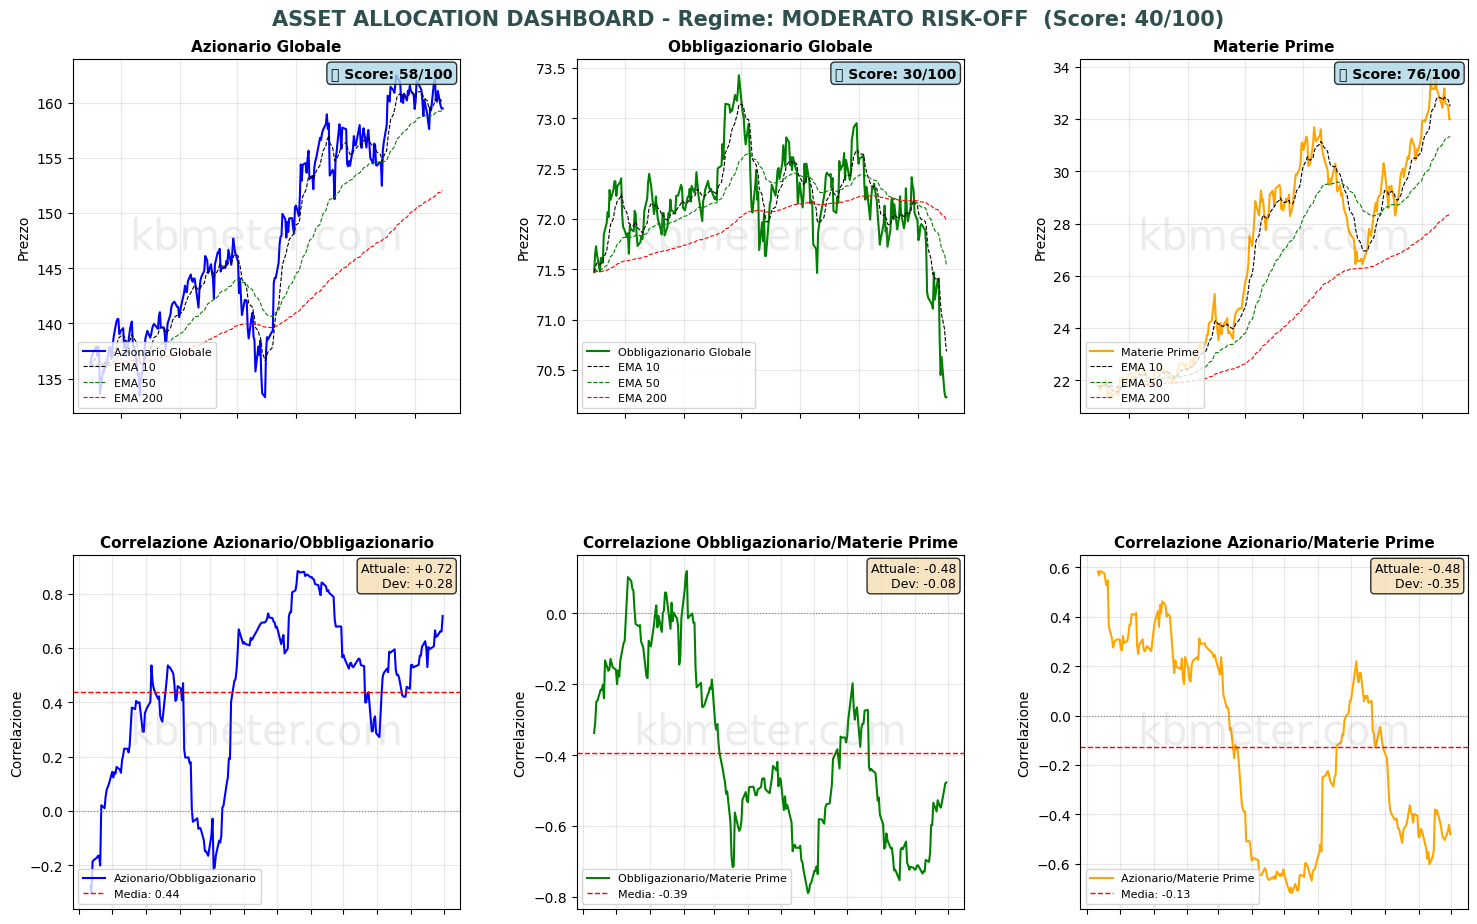
Looking at the individual asset classes, global equities are currently finding support at their medium-term moving average, while fixed income is stabilizing around the lows of the period. Volatility in the energy segment is pushing commodities below their short-term moving average, although they remain comfortably above their medium-term moving average.
Our market “weather map” continues to point to a neutral outlook for equities, while the reading for cryptocurrencies has softened slightly. Gold remains in negative territory. Overall, commodities are also losing momentum, although volatility in the energy sector and the significant weight of precious metals make the picture more difficult to interpret.
It is worth noting that 43% of the assets we monitor now have a Health Score between 35 and 45 points, with the average standing at 47 points. This points to a neutral environment, with somewhat more pronounced signs of weakness than a few weeks ago.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures point to moderately risk-on sentiment (+0.35% on average), with the US slightly positive (+0.31%), Europe slightly positive (+0.10%), and Asia positive (+0.57%).
📊 Global Futures – Pre-Market Sentiment
- Taiwan: +1.64%
- Nikkei 225: +1.02%
- DAX: +0.81%
- IBEX 35: -1.21%
- FTSE MIB: -0.32%
- Nifty 50: +0.06%
Macroeconomic calendar
Today is set to be a particularly interesting session from a macroeconomic perspective. This morning, investors will focus on Japanese industrial production data, Chinese PMI surveys, and, above all, September inflation figures from France, Italy, and Germany (to be assessed in light of yesterday’s higher-than-expected reading in Spain).
In the afternoon, the latest US PCE inflation data will be released, together with August 2026 figures for personal spending and personal income. The final reading of Q2 2026 GDP is also due.
On the earnings front, all eyes will be on Micron, which will report its results after the close of Wall Street.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 30 September 2026 - 8:19 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.
