Markets Brace for Central Bank Week as Inflation, Yields and AI Drive the Agenda
The week ahead is a crucial one for three of the world’s major central banks. The BoJ, Fed and BoE are all set to decide on interest rates, with the probability of a rate hike relatively high, at least in Japan and the US. Inflation, bond yields and monetary policy will therefore be among the key market movers across financial markets, while it will be interesting to assess the impact on the technology sector of the latest comments from AI leaders regarding the opportunity to slow down the race towards increasingly powerful models. The first signals coming from Asia are not encouraging. South Korea’s KOSPI is down between 2.5% and 3.1%, with the sell-off concentrated in AI-related semiconductor stocks: SK Hynix -5%, Samsung Electronics -2.9%, and Kioxia also sharply lower. Overall sentiment remains neutral with a risk-off bias, while futures point to a negative opening for the US and a positive one for Europe.
Market Weather Map
September 14, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
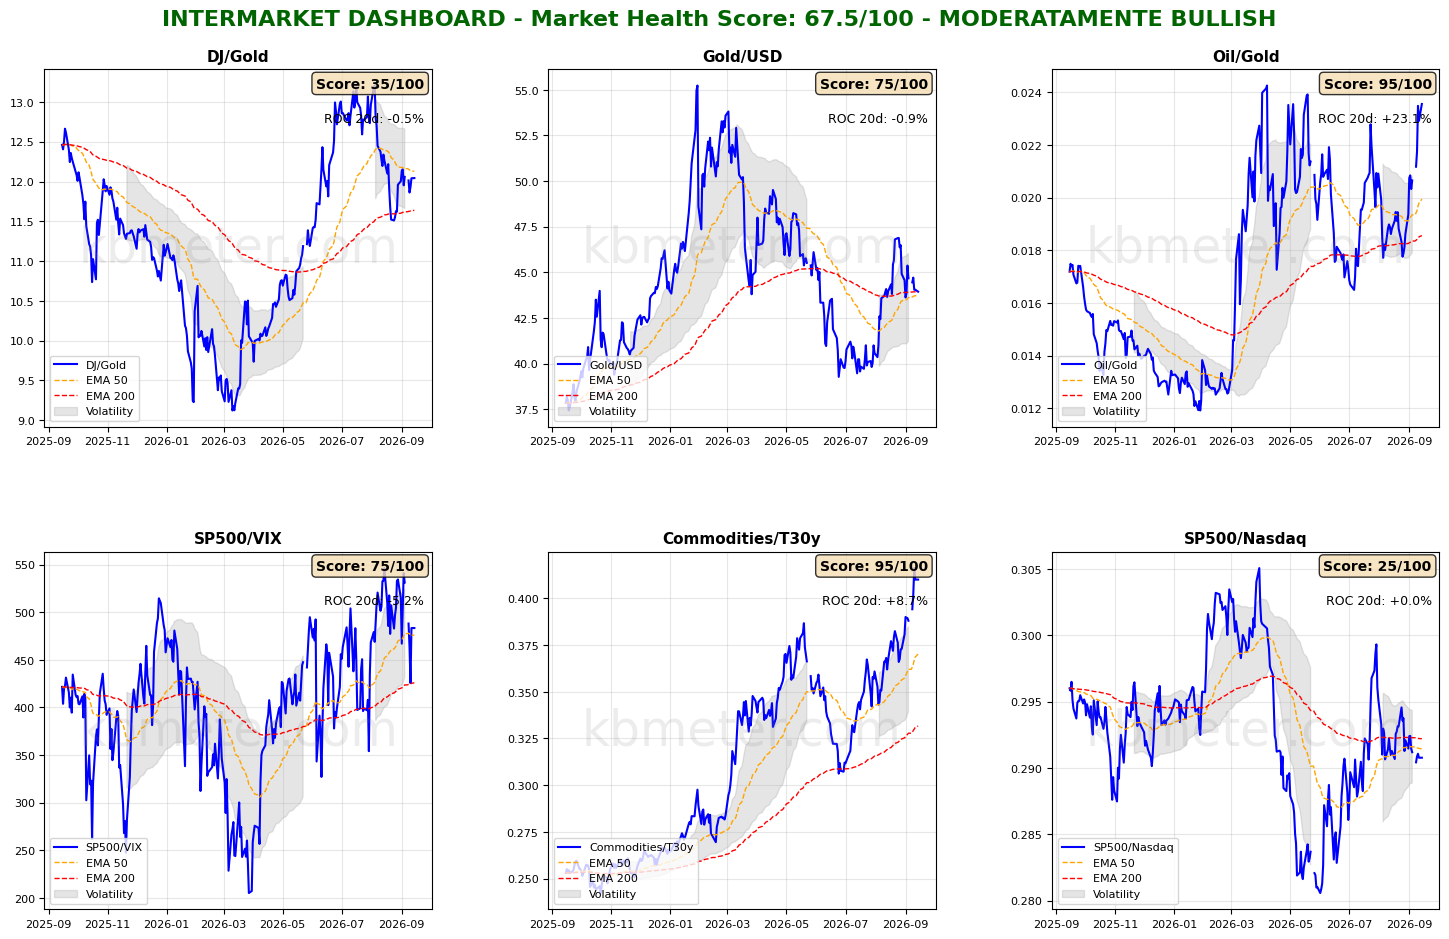
Financial markets are showing neutral sentiment today. Intermarket analysis points to a Market Health Score of 68/100. Inflation and bond yields remain key themes across markets, while our intermarket dashboards continue to closely monitor the Gold/Dollar and Commodities/Bonds ratios. The former remains at the support provided by its long-term moving average, with gold pricing in the almost certain rate hike by the Fed, while the dollar remains broadly stable. Commodities, driven by energy and food prices, continue to push the second ratio higher, supported by decidedly elevated yields on long-term US Treasuries.
Overall, sentiment remains in neutral territory. The S&P 500/VIX ratio remains highly volatile but above its long-term moving average, while the Dow/Gold ratio remains stable. Over the course of the week, the S&P 500/Nasdaq ratio will be worth monitoring, particularly following the latest comments from AI leaders regarding a possible slowdown in the development of increasingly powerful models. The first signals coming from Asia this morning are not reassuring.
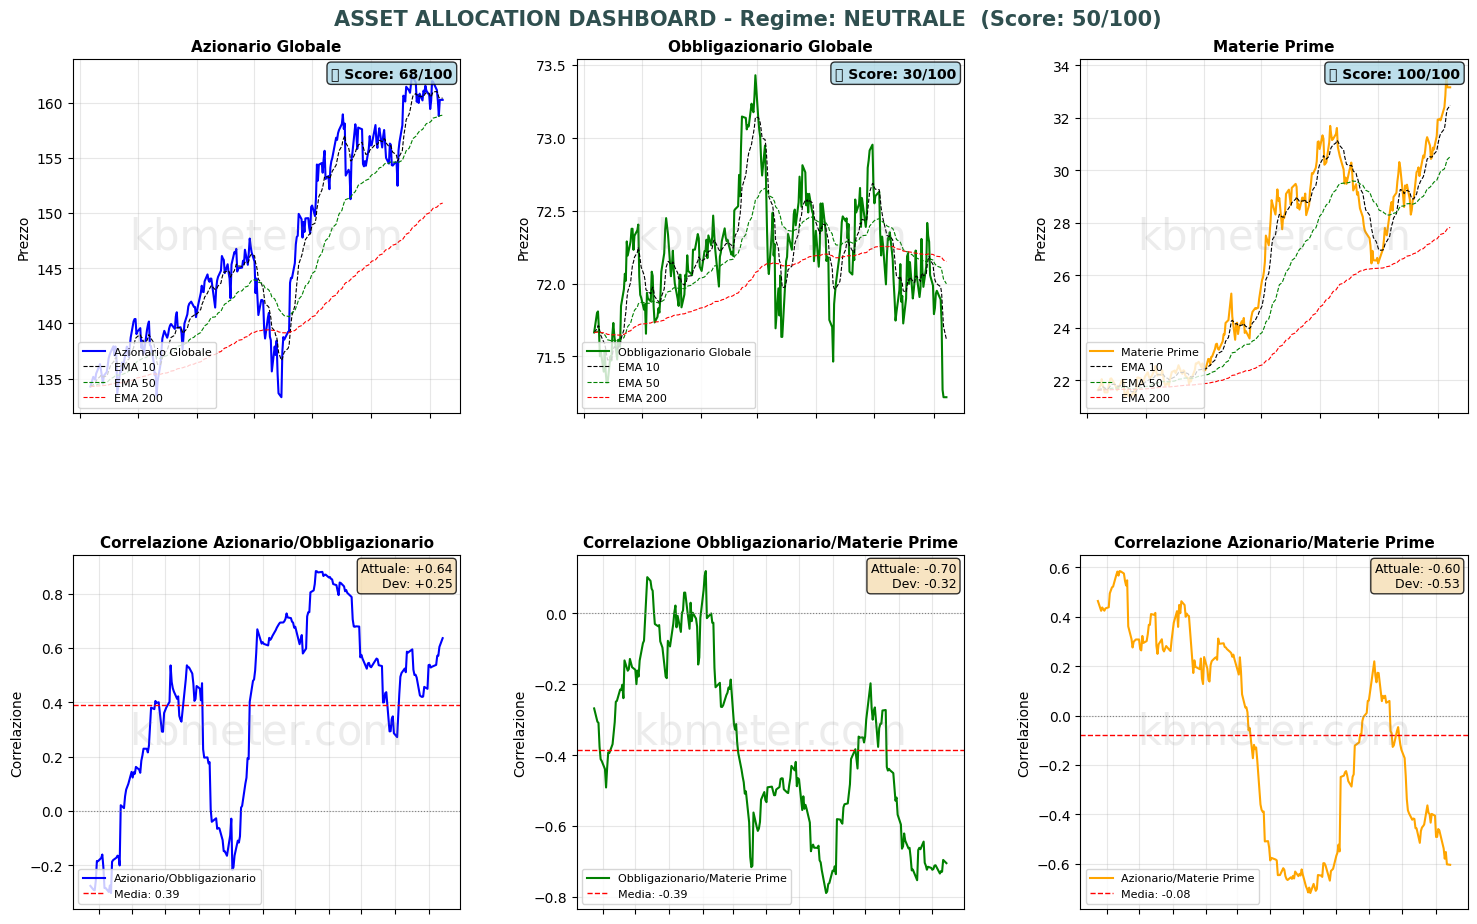
Our weather map, based on last Friday’s close, confirms the ongoing weakness in bonds and gold, while equities remain in neutral territory. Looking at weekly changes, and particularly at the momentum component of our score, we can see an acceleration in volatility across both fixed income and the European energy sector, with both showing a weekly increase of more than 15 points. On the other hand, the entire high-yield segment has recorded a decline of around 10 points in its momentum score. This is a move that warrants further assessment and close monitoring over the coming weeks.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures point to a moderately risk-off sentiment (-0.13% on average), with the US slightly negative (-0.48%), Europe slightly positive (+0.48%), and Asia negative (-0.88%).
📊 Global Futures – Pre-Market Sentiment
- FTSE MIB: +1.54%
- IBEX 35: +1.09%
- CAC 40: +0.65%
- Nikkei 225: -2.05%
- US Tech 100: -1.21%
- CSI 300: -0.96%
Macroeconomic calendar
On the macro front, today’s calendar does not feature any particularly significant data releases. Nevertheless, August inflation figures from Canada and India are worth watching. Further interesting insights could also emerge from comments by three members of the ECB Governing Council, including President Lagarde.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 14 September 2026 - 8:53 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.
