Markets Absorb Fed Hike, Weigh Duration of New Tightening Cycle; BoE in Focus Today
In the end, the Fed raised interest rates in line with financial market expectations. The rate hike had already been fully priced in, but it came against a backdrop of persistent inflation and the likely need for further action by the central bank. The debate surrounding the characteristics of this new Fed tightening cycle will therefore play a key role in shaping investors’ decisions over the coming weeks.
In the meantime, as also noted yesterday, little has changed at the long end of the yield curve. The week continues with another delicate event: the highly uncertain Bank of England meeting.
Sentiment across financial markets remains in neutral territory, with volatility contained. Futures point to a positive opening for both European and US markets.
Market Weather Map
September 17, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
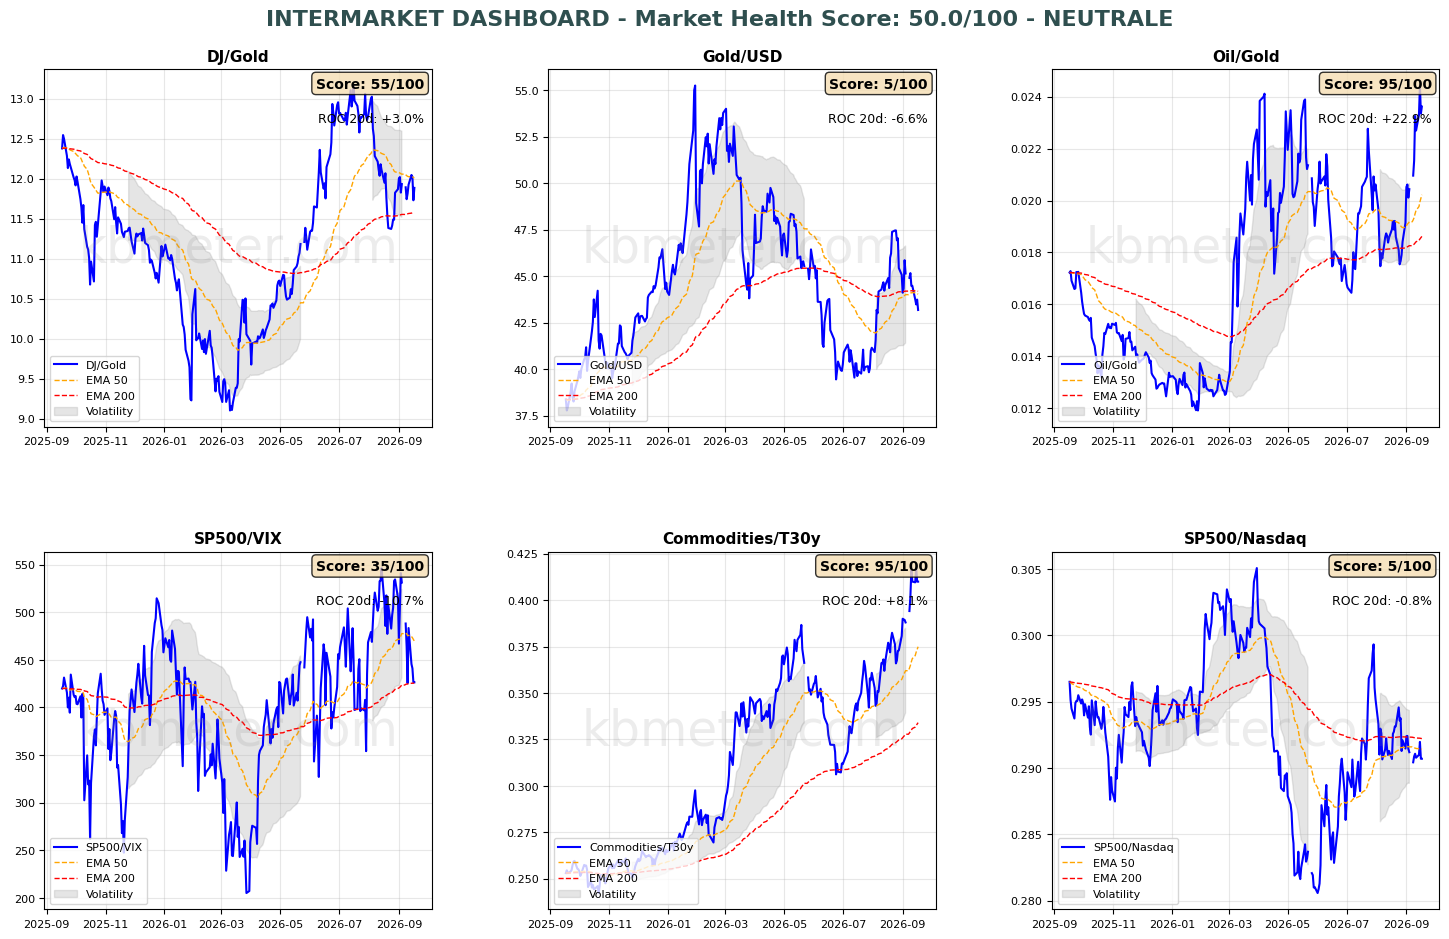
Financial markets are showing neutral sentiment today. Intermarket analysis points to a Market Health Score of 50/100. Our intermarket dashboards showed only minimal moves on the day of the Fed’s decision to raise interest rates. Risk appetite indicators remain broadly stable, while the Dollar/Gold ratio remains below its long-term moving average. Long-term yields continue to remain elevated, while the Commodities/Bond ratio remains firmly near its period highs.
In short, markets had already priced in the rate hike to a large extent, and the only real — and very negative — surprise would have been any outcome other than a rate increase.
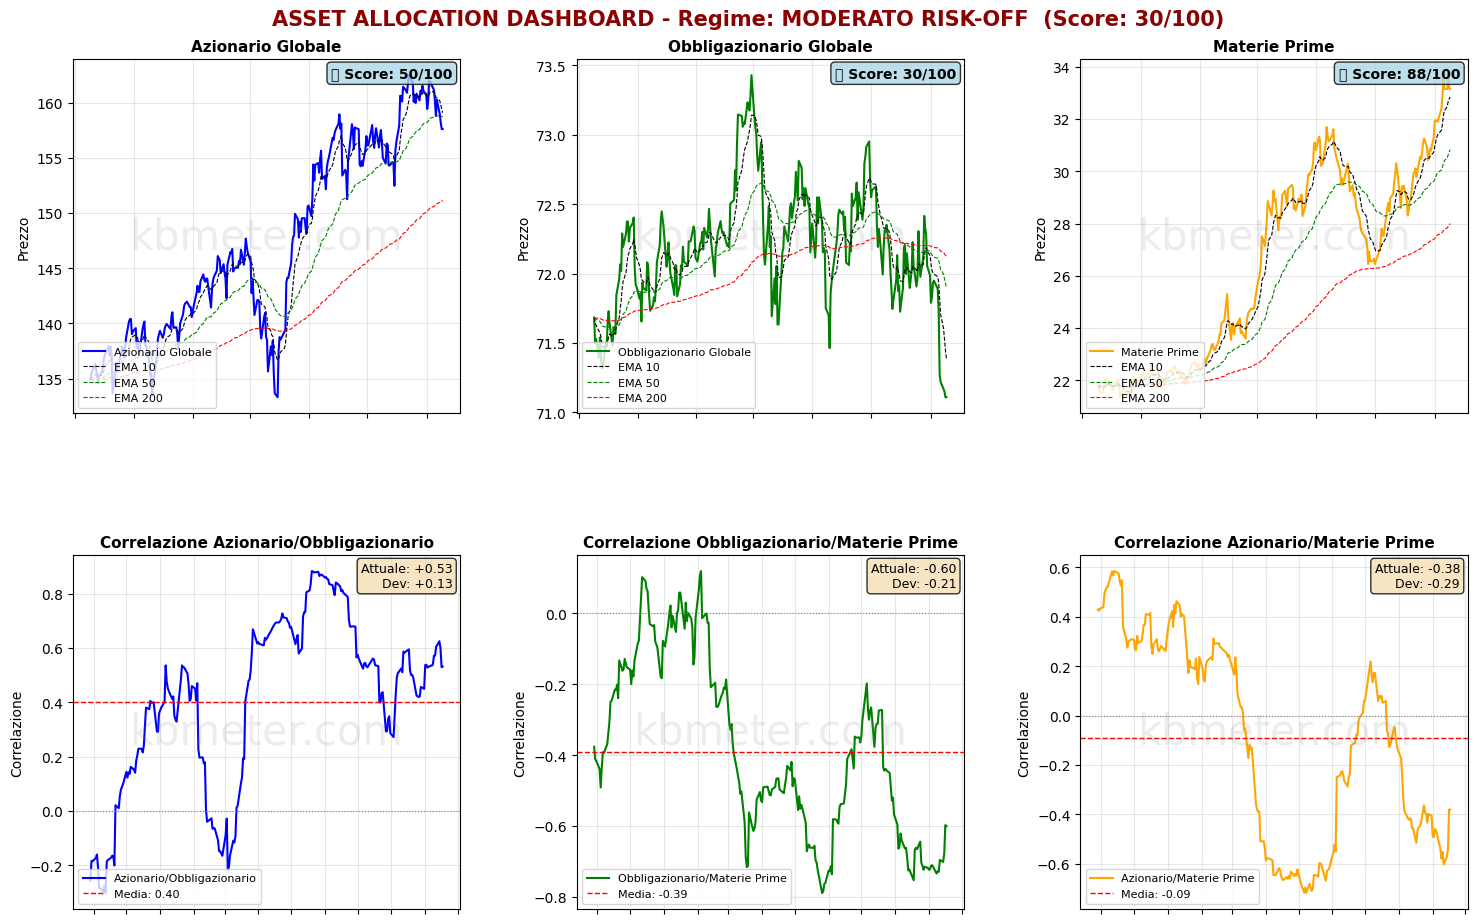
On the asset-class front, global equities remain in a critical area, just below their medium-term moving average. There are still no signs of meaningful change in either fixed income or commodities.
Our Weather Map confirms the overall picture, with equities still in neutral territory, while gold and bonds remain in negative territory.
The Dollar Index stands out, recording the largest seven-day increase in terms of Health Score. On the other hand, we highlight the cooling in copper, reflecting lower supply-side pressures: its Health Score has fallen by 15 points over the past week. Copper therefore joins emerging-market equities among the areas showing the weakest seven-day changes.
Global Futures – Pre-Market Sentiment
Pre-Market Futures. Global futures are signaling risk-on sentiment (+0.51% on average), with the US positive at +0.66%, Europe positive at +0.52%, and Asia slightly positive at +0.20%.
📊 Global Futures – Pre-Market Sentiment
- Taiwan: +1.11%
- CAC 40: +0.82%
- US Tech 100: +0.70%
- Nikkei 225: -0.46%
- IBEX 35: +0.14%
- Nifty 50: +0.20%
Macroeconomic calendar
Central banks remain in the spotlight. Today it is the Bank of England’s (BoE) turn to decide on interest rates. Macroeconomic data would suggest another pause, but the strong division seen at the July meeting makes today’s decision extremely uncertain. This afternoon, the US will release the September Philly Fed manufacturing index, the latest figures on initial jobless claims, and August housing starts.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 17 September 2026 - 10:28 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.
