Bond-Yield Pressure Persists as Dollar Rises and Gold Falters; Markets Await Key Macro Data
The narrative across financial markets remains unchanged. Inflationary pressures, and other factors, continue to push bond yields higher and raise interest-rate expectations. The dollar rises to a Health Score of 68, its highest level in a year, while gold remains below the 40-point threshold, reflecting the impact of this market configuration. Equities are currently holding in neutral territory, but the first interesting macroeconomic data of the week will be released today, including inflation in Spain and US job openings. The key challenge for investors is to assess whether, and to what extent, inflation could begin to erode the economy’s growth prospects. Overall sentiment remains in neutral territory, while futures point to a below-par opening for both European and US markets.
Market Weather Map
September 29, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
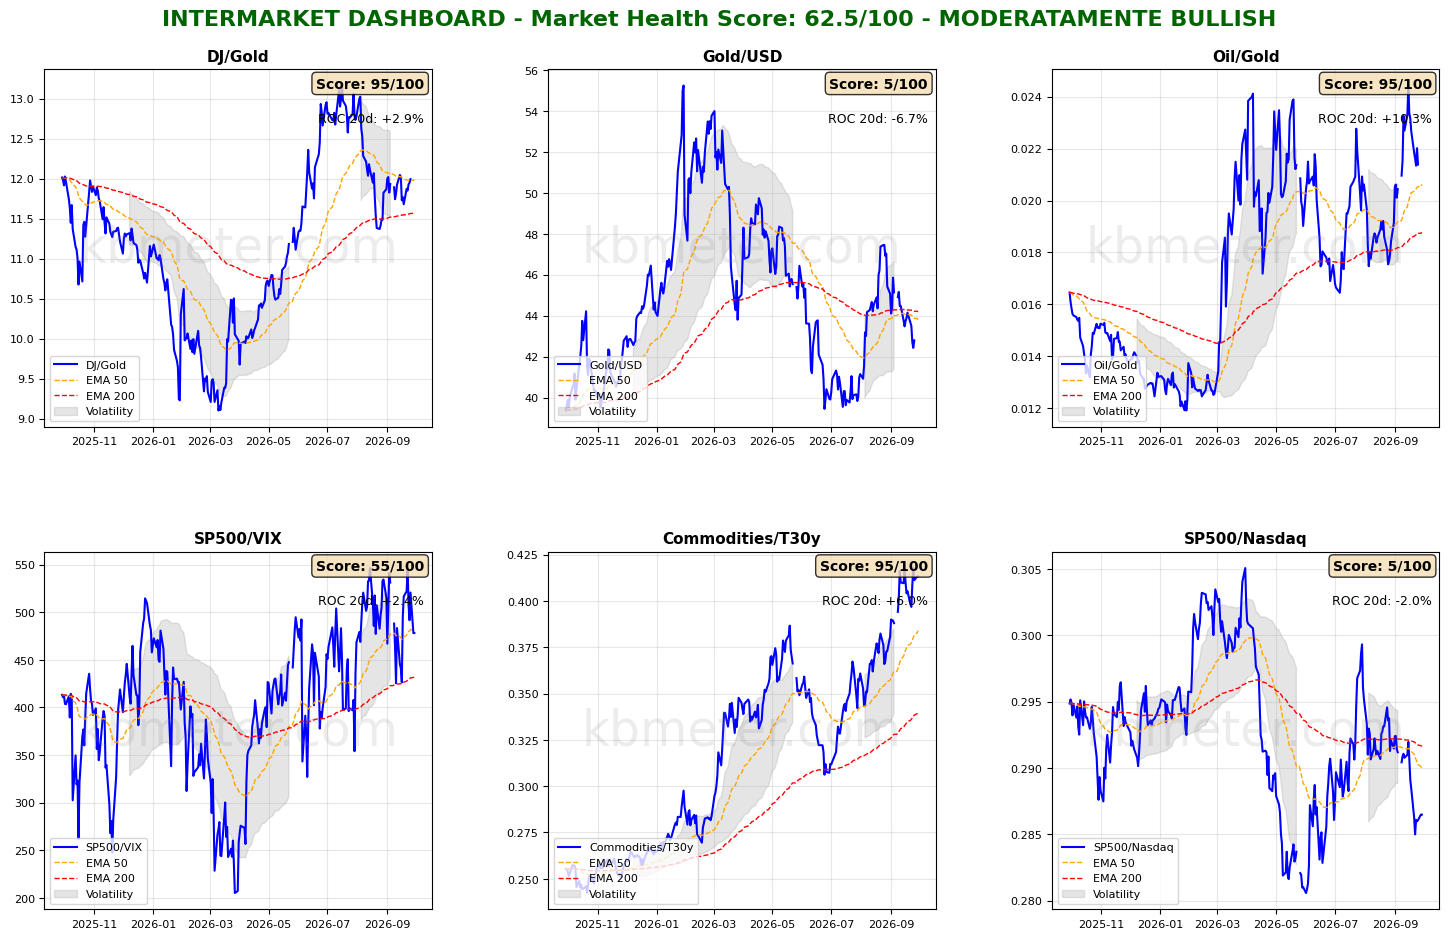
Financial markets are showing neutral sentiment today. Intermarket analysis points to a Market Health Score of 62/100. Among the intermarket dashboards, the most significant relationship today is the one between Commodities and the 30-year Treasury. The ratio that tracks inflation expectations has returned to its period highs, driven by strong upward pressure on bond yields. Oil is gaining ground against gold, while on the equity side, risk appetite remains in positive territory, albeit with a slight weakening.
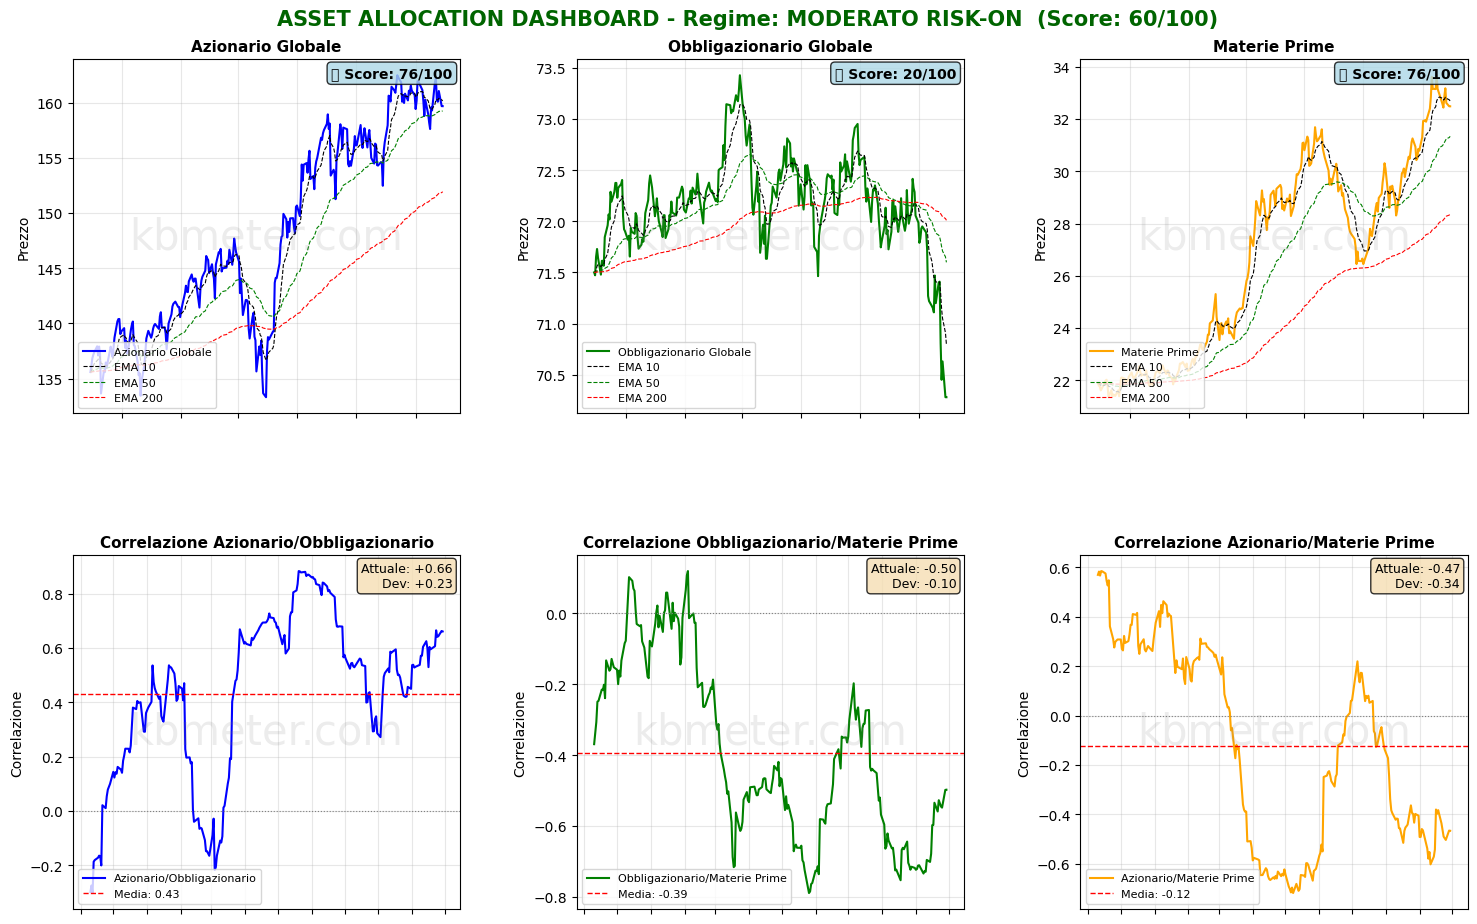
The picture across asset classes remains broadly unchanged. Global bonds continue to lose ground, while equities have fallen below their short-term moving average and are now “targeting” the considerably more important 50-day moving average. Commodities remain near their highs, with their performance balanced by the strength of oil and the weakness of precious metals.
Our market “weather map” confirms the picture. The dollar rises to a score of 68, reaching its highest one-year reading and recovering 28 score points in a single month. However, this move is taking place on declining volumes, an element that should be taken into consideration. Equities remain in neutral territory, with the US technology sector outperforming the broader equity market in the region by more than 10 points.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures are signaling moderately risk-off sentiment (-0.49% on average), with the US slightly negative (-0.30%), Europe slightly negative (-0.06%), and Asia significantly negative (-1.36%).
📊 Global Futures – Pre-Market Sentiment
- FTSE MIB: +0.31%
- Euro Stoxx 50: +0.14%
- DAX: -0.01%
- CSI 300: -2.28%
- Taiwan: -1.43%
- Hang Seng: -0.95%
Macroeconomic calendar
The macroeconomic day opened with the Reserve Bank of Australia (RBA) raising interest rates, in line with market expectations. Today’s key releases to monitor include preliminary September inflation figures in Spain, the Eurozone Economic Sentiment Indicator, US house price data for July, US job openings for August, and the Conference Board’s US Consumer Confidence Index for September.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 29 September 2026 - 8:21 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.
