Volatile Financial Conditions as Yields, Debt Debate Temper Risk-On Sentiment
Financial market conditions remain volatile. The attempt at a risk-on recovery has encountered new obstacles amid renewed tensions in the Middle East and growing debate over the sustainability of France’s public debt. The latter has fueled—despite the lack of any concrete evidence—the specter of contagion risk across the region, weighing particularly heavily on the financial sector.
In reality, our intermarket indicators and Health Scores do not point to any sharp moves compared with previous analyses. With little in the way of macroeconomic catalysts today, investors will focus on the Fed minutes (with another rate hike by year-end now virtually priced in) and the ECB minutes, due today. Futures point to another negative opening for European markets, while US markets are expected to open broadly flat.
Market Weather Map
October 8, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
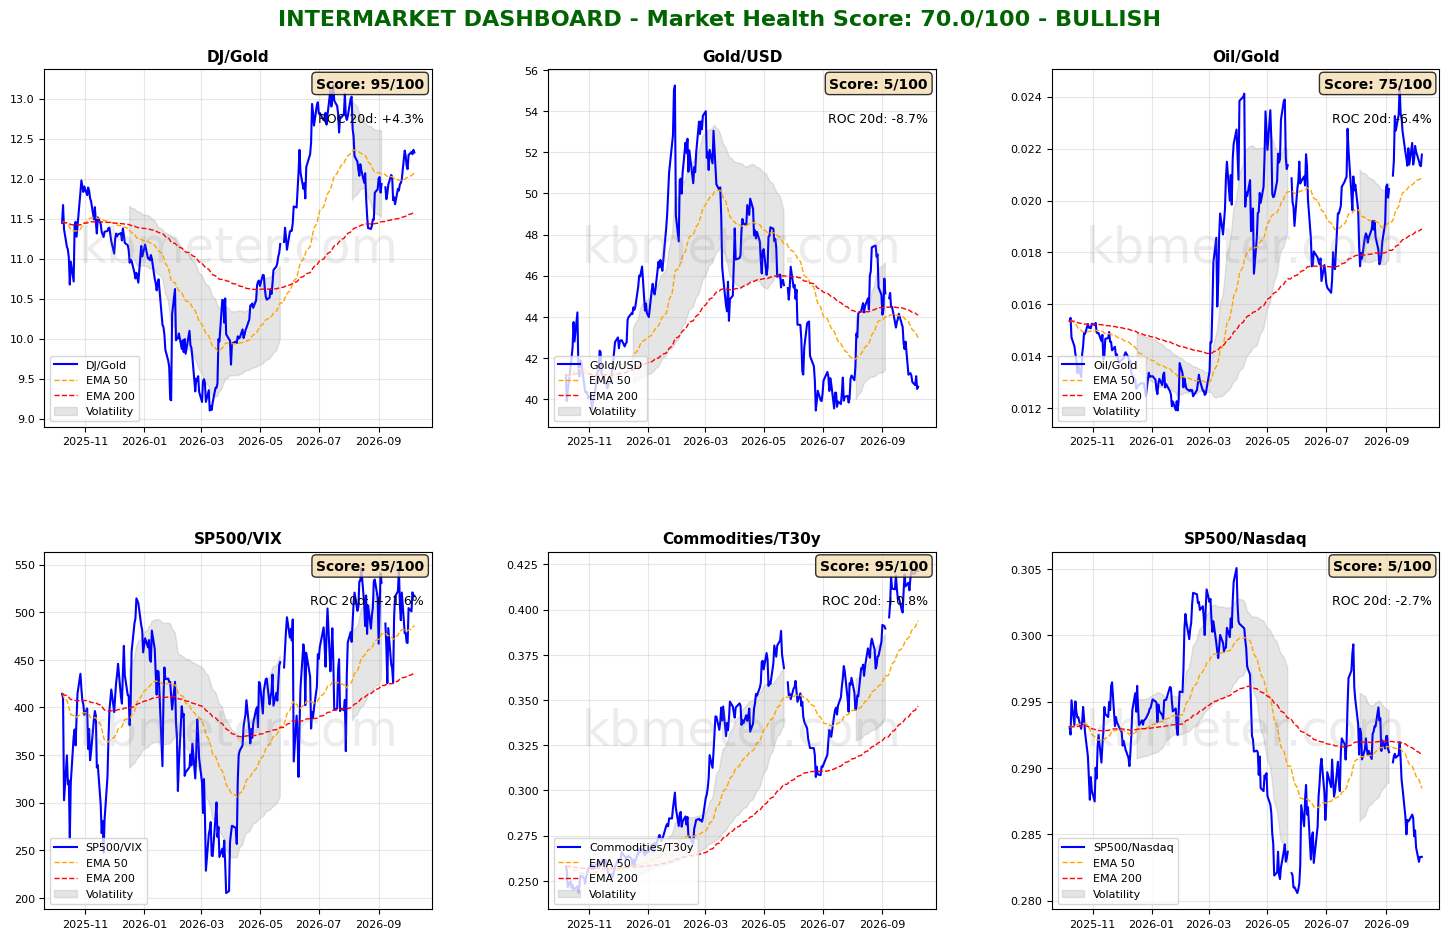
Financial markets are showing a neutral sentiment today. The intermarket analysis shows a Market Health Score of 70/100. Despite yesterday’s slowdown, our intermarket dashboards continue to signal a broadly wait-and-see stance across financial markets, with the main ratios having remained largely unchanged for several sessions.
Risk appetite therefore remains in positive territory, while the Commodities/Bonds ratio remains near its period highs. Gold, oil and the US dollar are also broadly holding their current positions.
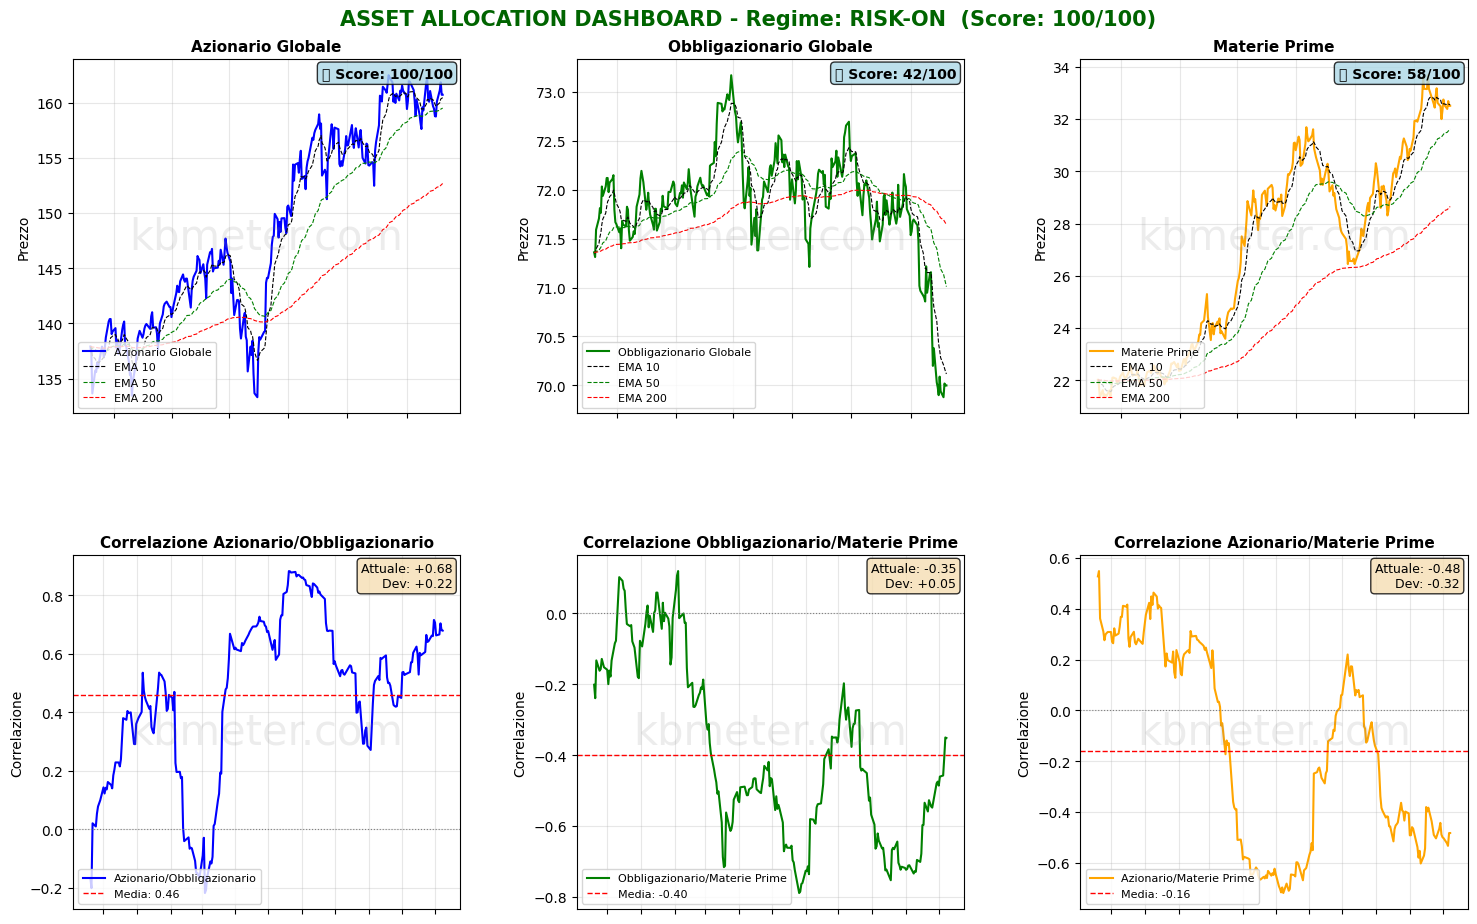
As for the various asset classes, yesterday’s decline nevertheless leaves global equities above their key reference moving averages. Bonds remain in the bottoming area—although it is still unclear whether this is temporary or more structural—as already highlighted yesterday. Commodities are moving higher, with short-term sideways momentum offsetting the opposing forces between energy and agricultural commodities on the one hand and precious metals on the other.
Our market weather map continues to show the equity sector in neutral territory, with US equity markets in better shape than their European and Asian counterparts. Notably, the technology sector has shown a degree of score volatility, recovering to the 60-point area yesterday thanks to an improvement in momentum and outlook indicators.
On the fixed-income front, we are seeing a widening of the spread between Investment Grade and High Yield scores, both in the United States and Europe.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures point to a moderately risk-off sentiment (-0.41% on average), with the US slightly negative (-0.07%), Europe negative (-0.71%), and Asia slightly negative (-0.07%).
📊 Global Futures – Pre-Market Sentiment
- CSI 300: +0.27%
- DAX: -0.01%
- US Tech 100: -0.01%
- FTSE MIB: -2.55%
- IBEX 35: -1.50%
- Taiwan: -1.01%
Macroeconomic calendar
The macroeconomic calendar offers few major catalysts today. Key events include the latest US jobless claims data, Germany’s August 2026 export figures, a speech by the BoE Governor, Mexican inflation data, and the minutes of the ECB’s latest meeting.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 8 October 2026 - 8:16 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.