US Inflation in Focus as Early Earnings Fail to Lift Market Sentiment
Financial markets are awaiting the US inflation data for September 2026, while cautiously welcoming the results of the first quarterly earnings reports from the banking sector. Goldman Sachs, Wells Fargo and Citi have beaten expectations, while JPMorgan reported figures slightly below forecasts. Another round of earnings is due today, including those from Bank of America (recently fined by the US Treasury), Morgan Stanley and BlackRock.
Turbulence continues in the technology sector, which has fallen below the 50-point health score threshold in just a few days. Investor sentiment remains in neutral territory, while futures point to a positive open in both the United States and Europe.
Mappa Meteo dei Mercati
October 14, 2026
Azionario USA
Azionario Europa
Azionario Asia
Materie Prime
Obbligazioni
Indice Dollaro
Tecnologia
Oro
Petrolio
Criptovalute
Riepilogo Mercati
Vuoi vedere il dettaglio score per tutti gli oltre 100 asset monitorati da KBMeter?
Prova gratis 14 giorni →Il sentiment sui mercati finanziari
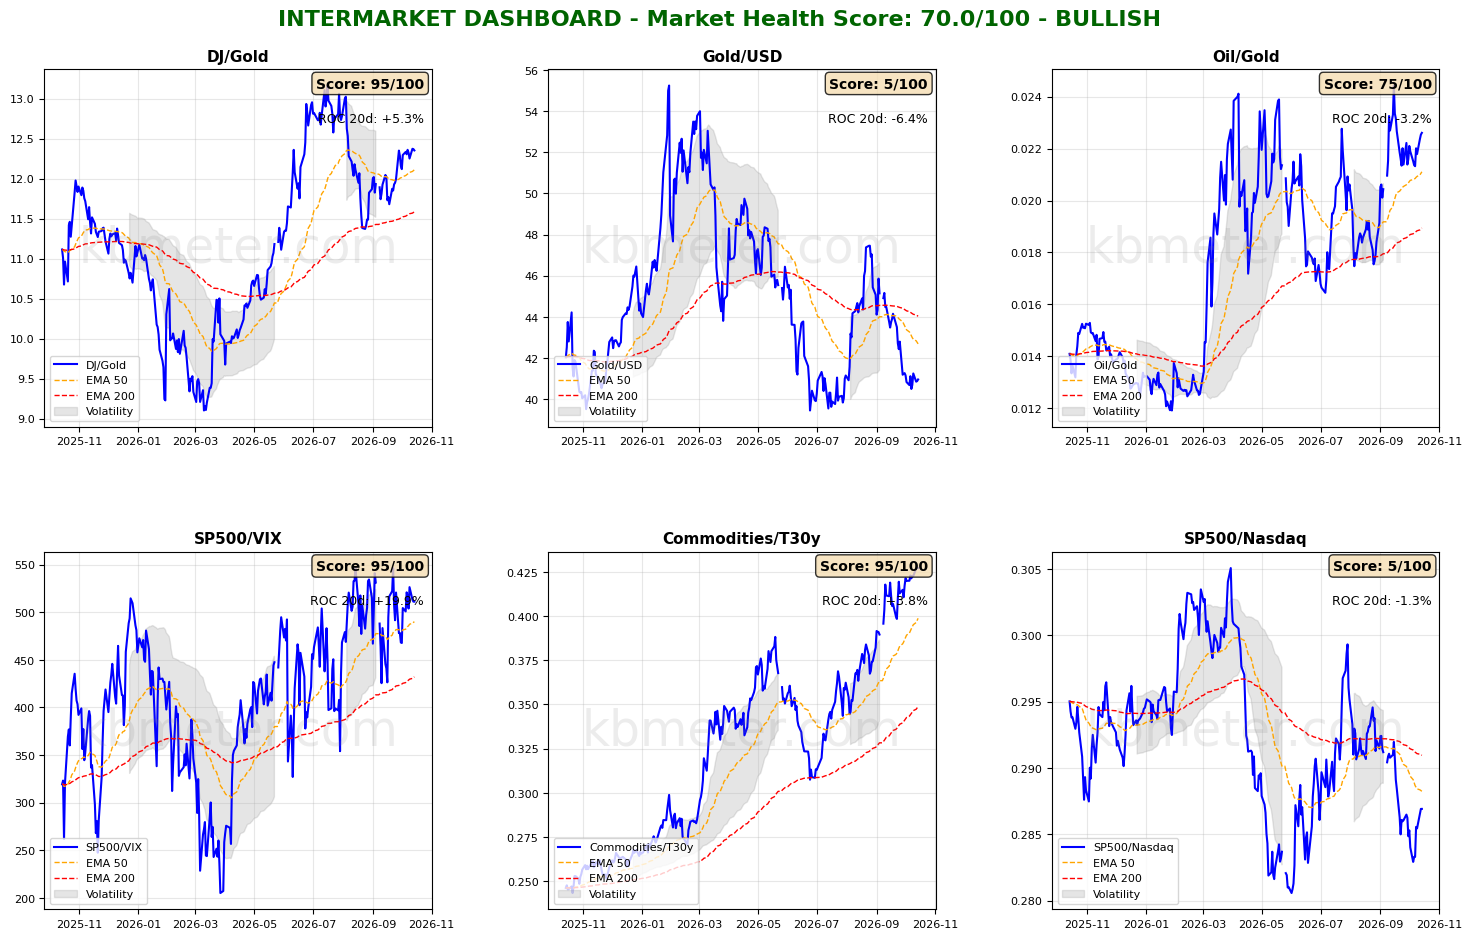
Financial markets are currently showing neutral sentiment. Intermarket analysis puts the Market Health Score at 70/100. Our intermarket dashboards continue to point to an overall stable environment compared with previous assessments.
The only notable move concerns the Oil/Gold ratio, which has resumed its upward trend after a period of sideways trading. Otherwise, risk appetite remains stable and moderately positive, while the S&P 500/Nasdaq ratio continues to rebound and is approaching the critical threshold represented by its medium-term moving average. Upcoming earnings reports from the Magnificent Seven could play a decisive role in determining the ratio’s future direction and the outlook for the US technology sector. The upward trend in the Commodities/Bonds ratio also remains intact, continuing to be supported by bond yields.
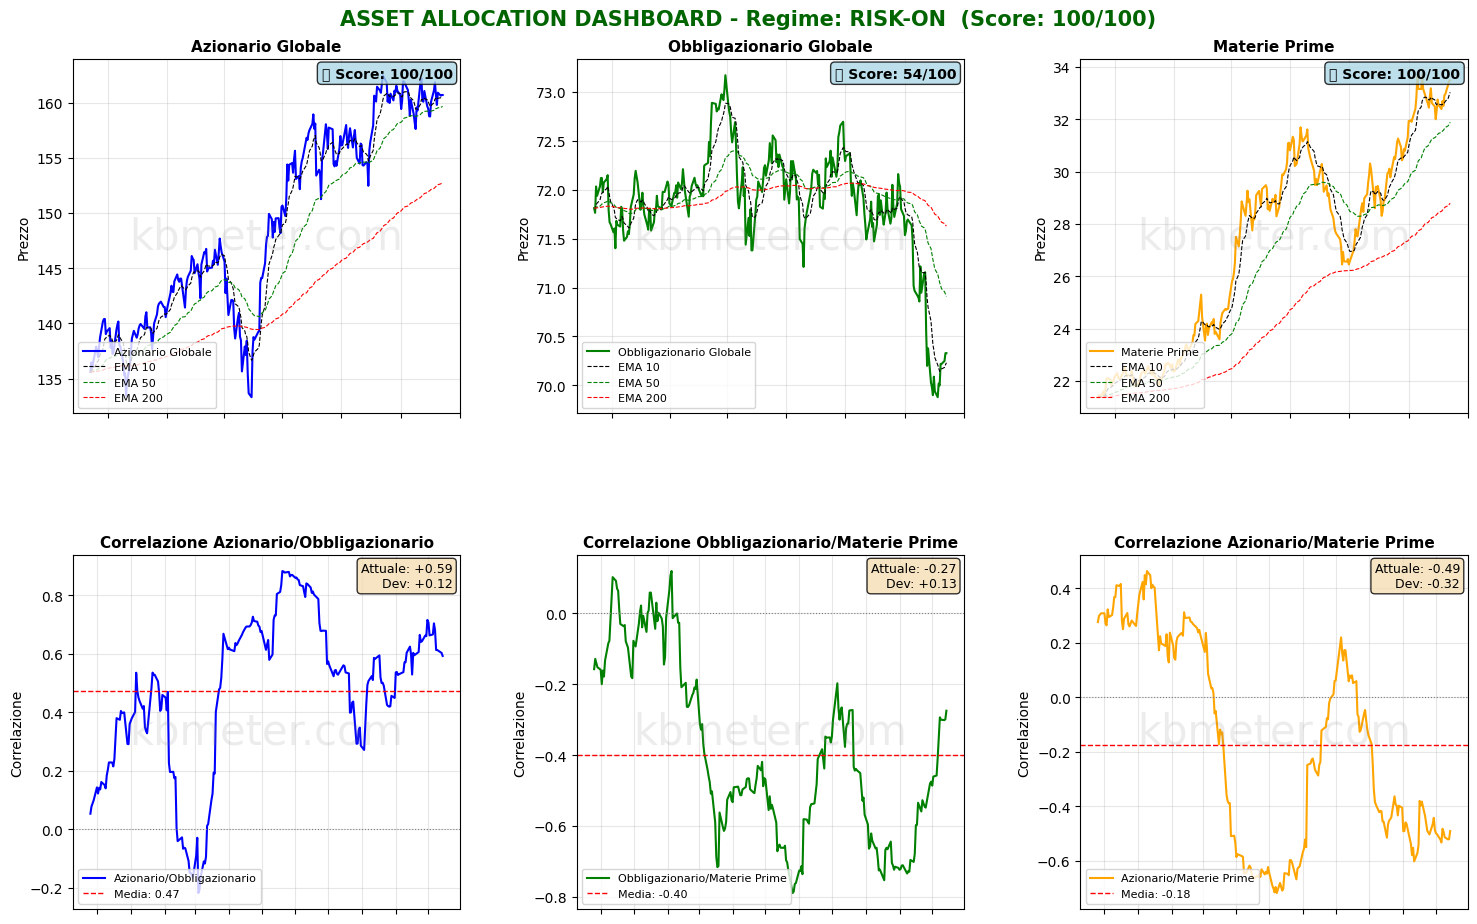
There are no major developments across asset classes. The attempt to form a bottom in global bonds remains in place, while global equities continue to move through a consolidation phase. Commodities remain near their period highs.
Finally, a look at the market weather map reveals few new developments. Equities remain in neutral territory, while the S&P 500 technology sector has slipped below the 50-point threshold. The Nasdaq’s score of 47 confirms this trend, with Monday’s sharp sell-off in Asian technology markets weighing on the sector. The US dollar maintains a positive assessment, while gold shows slight improvement, although precious metals as a whole remain firmly below the 50-point threshold.
Cosa dicono i futures
Pre-Market Futures: Global futures point to a moderately risk-on sentiment, with an average gain of 0.15%. US futures are slightly positive (+0.17%), European futures are marginally higher (+0.09%), and Asian futures are up slightly (+0.17%).
📊 Global Futures – Pre-Market Sentiment
- Taiwan: +0.98%
- DAX: +0.40%
- Hang Seng: +0.39%
- Nifty 50: -0.38%
- CSI 300: -0.24%
- IBEX 35: -0.14%
La giornata macro
On the macroeconomic front, the main focus today is the US inflation report for September 2026. Investors will also monitor inflation and export data from China, as well as the latest update on the average rate for 30-year mortgages in the United States.
On the corporate earnings front, today’s releases include results from Bank of America, Morgan Stanley, BlackRock, State Street and Progressive.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 14 October 2026 - 8:52 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.