Oil and Tech Stocks Drive Markets Higher as Week Gets Underway
Overall sentiment across financial markets remains in neutral territory, and the strong start to the week on the equity front has done little to dispel the many uncertainties that are still present. In the absence of major macroeconomic data releases, oil and the technology sector are the key drivers at the start of the week: the former is oscillating between hopes of a resumption of negotiations between the US and Iran and the risk of a broader escalation of the conflict; the latter is, at least for now, putting concerns over the future of AI on the back burner and welcoming Meta’s newly launched AI agent. Global equities and bonds opened the week with a rebound, while futures are pointing to a positive opening today for both Europe and the United States.
Market Weather Map
September 22, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
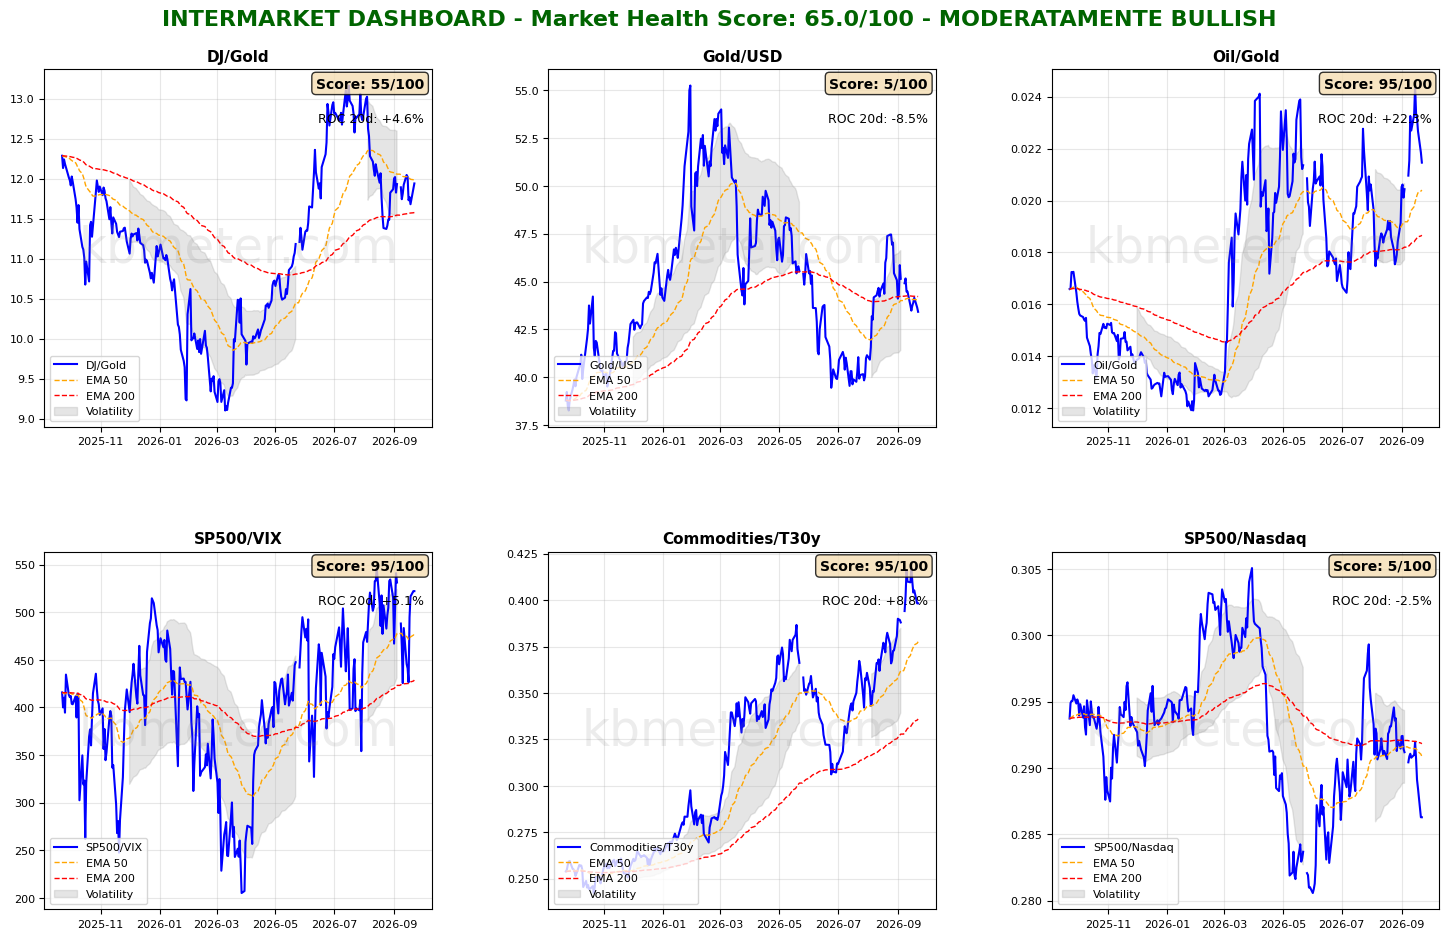
Financial markets are showing neutral sentiment today. Intermarket analysis points to a Market Health Score of 65/100. The most interesting signal in our intermarket dashboards is undoubtedly the S&P 500-to-Nasdaq ratio. In a single trading session, the ratio has moved back to the levels seen last July, with Meta’s announcement of its new AI agent sweeping away last week’s tensions and reigniting risk-on sentiment across equity markets. Another factor is also providing support, as highlighted by the Oil/Gold ratio: crude oil is losing ground relative to gold, which remains broadly stable even against the US dollar, amid expectations that diplomacy may regain momentum over the coming days in relation to the Middle East situation. Inflation expectations remain near their period highs, while the Dow/Gold ratio remains within the range defined by its medium- and long-term moving averages.
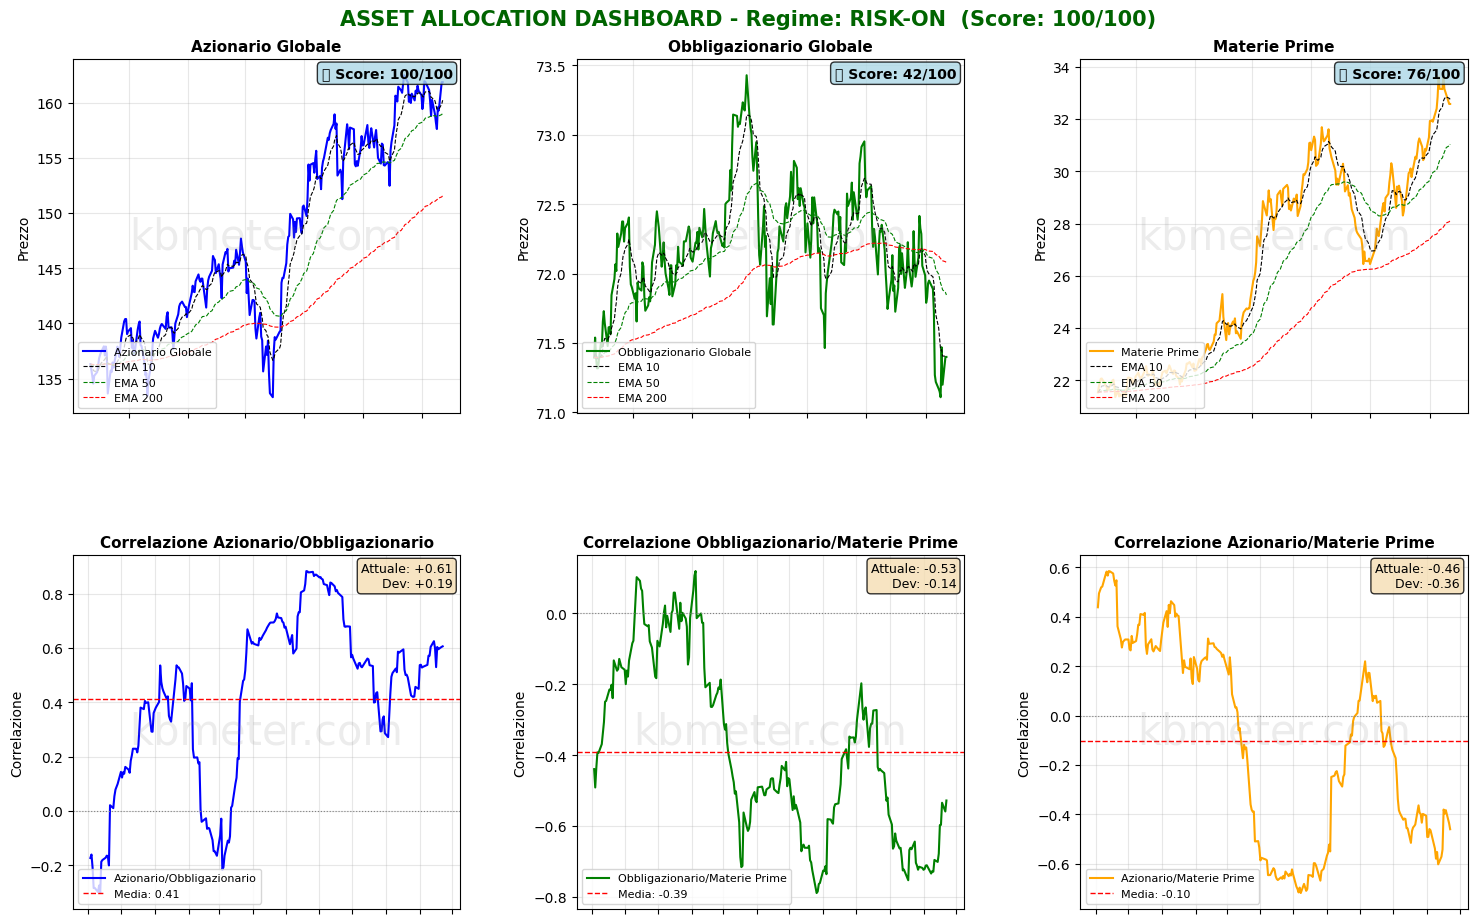
At the asset-class level, the combined effect of renewed confidence in the technology sector and hopes on the geopolitical front is clearly visible. Global equities and global bonds are rebounding from the levels reached towards the end of last week, while the rally in commodities is losing momentum.
Our market weather map confirms the picture. The technology sector has jumped above a score of 60, a level shared with the US dollar, while bonds have moved back above 40 points. In terms of weekly changes, the Growth-versus-Value style ratio is worth monitoring, with the spread appearing to widen in favour of Growth.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures are signalling moderately risk-on sentiment (+0.37% on average), with the US slightly positive (+0.04%), Europe positive (+0.67%), and Asia slightly positive (+0.21%).
📊 Global Futures – Pre-Market Sentiment
- FTSE MIB: +2.06%
- IBEX 35: +1.48%
- Taiwan: +0.82%
- Nikkei 225: -0.09%
- Nifty 50: -0.05%
- Russell 2000: -0.05%
Macroeconomic calendar
Another day with limited macroeconomic catalysts. Euro area consumer confidence will be worth monitoring.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 22 September 2026 - 8:41 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.
