Markets Week Heats Up: Big US Bank Earnings, Fresh Semiconductor Sell-Off — and Value Makes a Comeback
The trading week is gathering momentum. Ahead of the first major batch of earnings reports (Citigroup, JPMorgan and Wells Fargo), investors are weighing the latest figures from the IMF’s World Economic Outlook against a fresh wave of selling pressure in the semiconductor sector. Sentiment remains in neutral territory, although the sharp weekly increases in the scores for the value style and consumer staples—both traditionally defensive areas—are worth noting. Futures point to a slightly positive open in Europe and a marginally lower start in the United States.
Market Weather Map
October 13, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
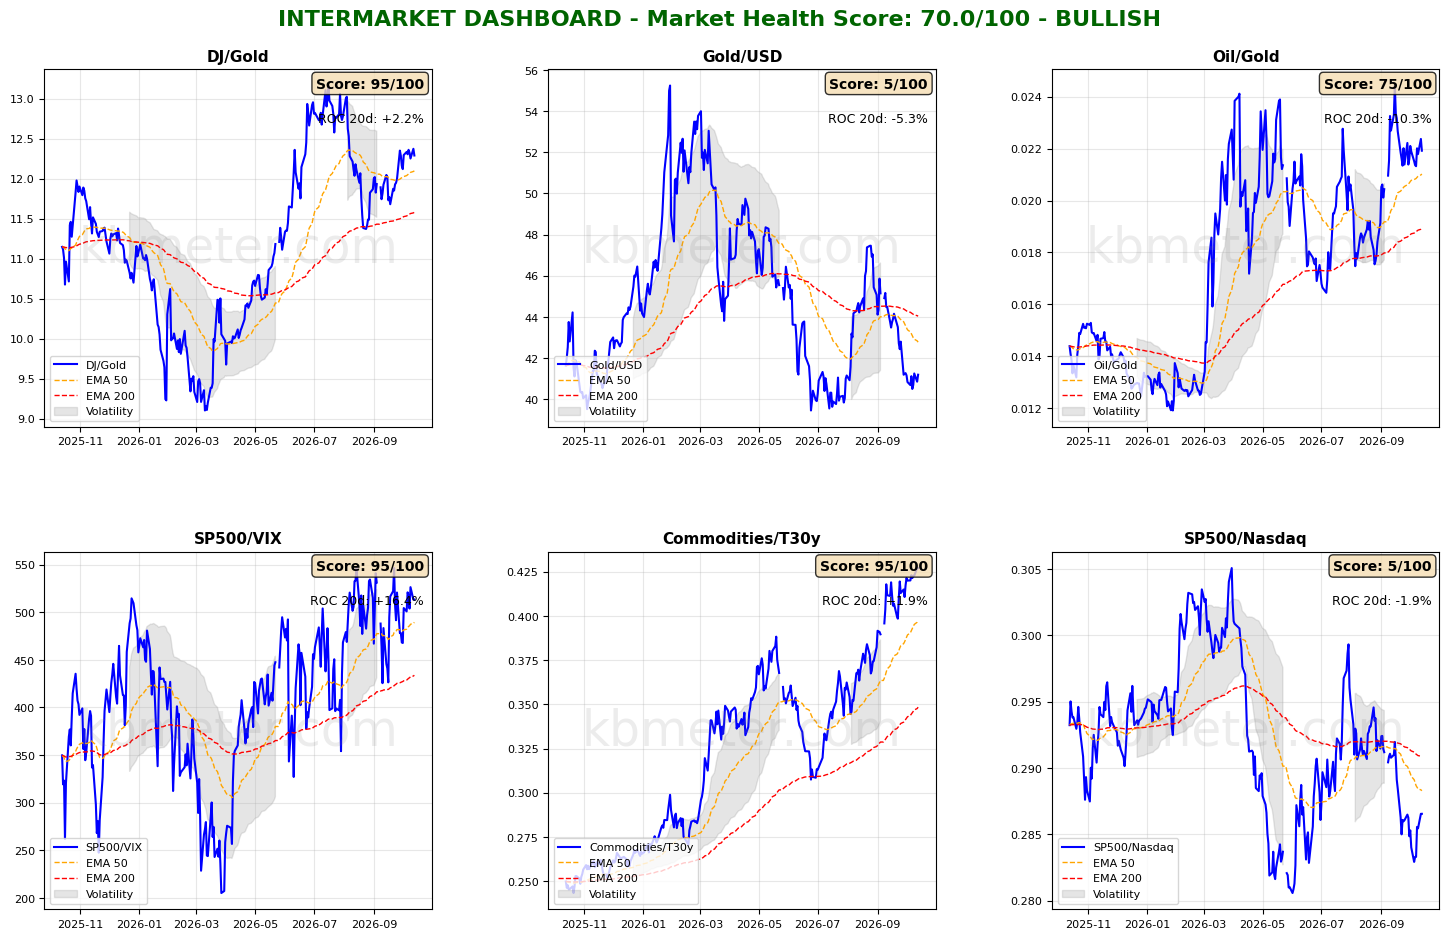
Financial markets are currently showing neutral sentiment. Intermarket analysis puts the Market Health Score at 70/100. Our intermarket dashboards remain broadly stable, with few changes compared with previous readings and no significant signals. Ahead of earnings season and the latest US inflation data, attention is focused on the resilience of current risk appetite, with both indicators having weakened, and on the evolution of inflation expectations.
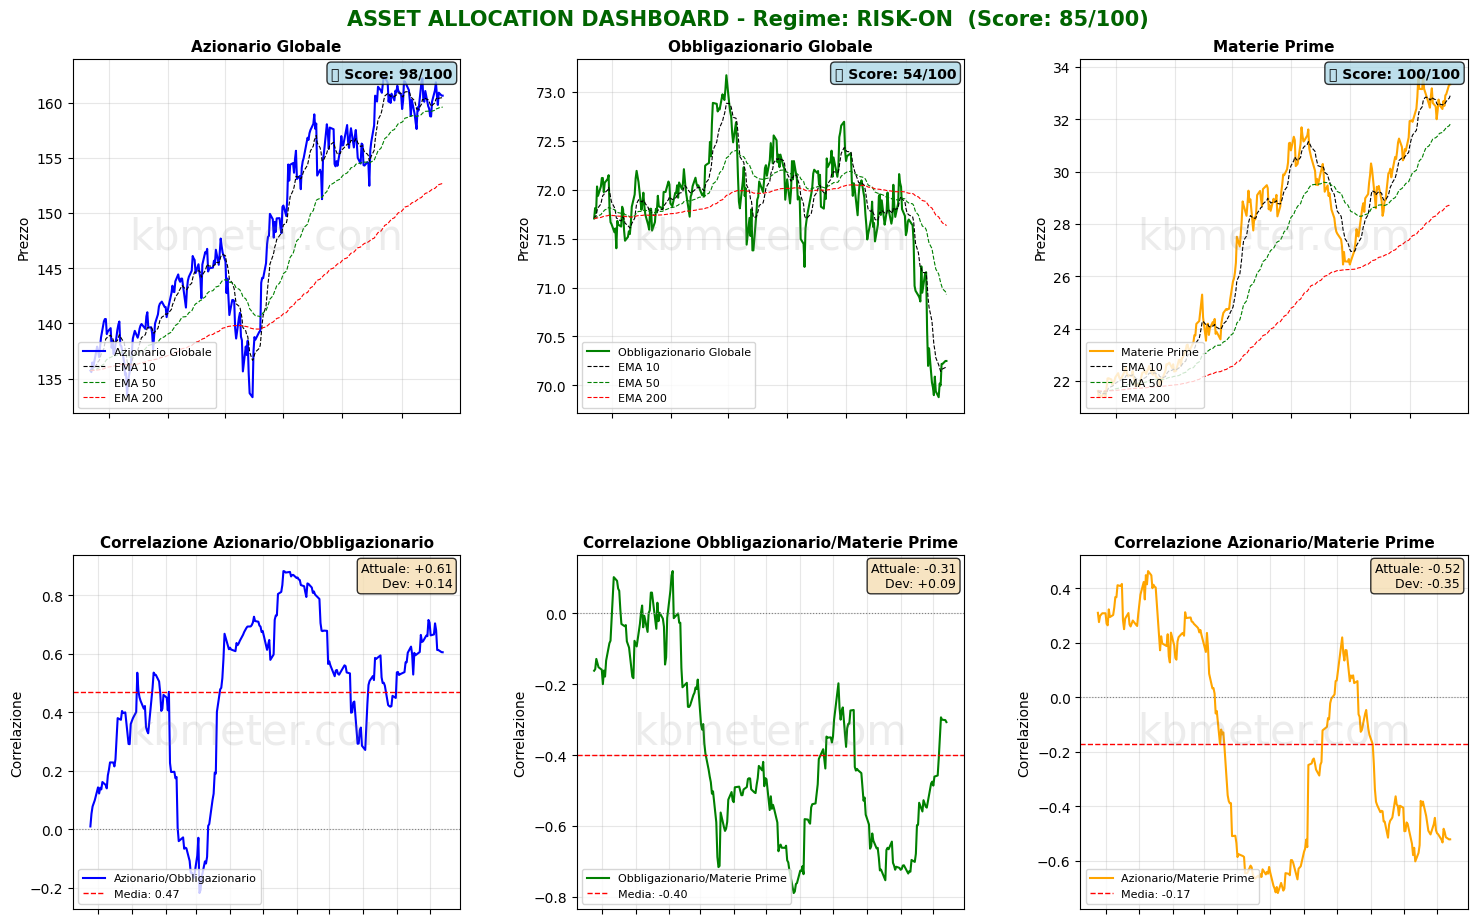
The picture across asset classes is virtually unchanged. Global equities remain above their key moving averages, although price movements have become much more subdued. Global bonds have moved above their short-term moving average and appear to be in a wait-and-see phase. The bottoming scenario remains on the table, but further confirmation is needed, along with a move back towards the medium-term moving average. Commodities remain near their recent highs.
Our market weather map confirms that equities remain in a neutral phase, with the technology sector losing momentum amid renewed signs of selling pressure, while the US dollar remains the only asset class with a score above 60. Commodities and bonds are stable and remain below the 50-point threshold.
The US financial sector is entering earnings season with neutral scores for the industry’s major players, while regional banks remain in negative territory, with a score of 39.
Looking at weekly changes, two assets traditionally associated with a more cautious investor stance stand out. The value style has surged by 18 points in seven days, moving back ahead of growth, with both styles now scoring above 60. Consumer staples have gained more than 20 points over the same period, climbing well above the 60-point threshold and opening up a 15-point lead over consumer discretionary.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures point to a moderately risk-off sentiment, with an average move of -0.09%. US futures are slightly lower (-0.14%), European futures are modestly higher (+0.27%), while Asian futures are in negative territory (-0.61%).
📊 Global Futures – Pre-Market Sentiment
- IBEX 35: +1.62%
- Nifty 50: +1.13%
- FTSE MIB: +0.32%
- Taiwan: -1.70%
- Nikkei 225: -1.01%
- US Tech 100: -0.79%
Macroeconomic calendar
Another day with few notable macroeconomic catalysts lies ahead. Aside from the IMF’s World Economic Outlook figures, investors will be watching Germany’s final September inflation data, UK retail sales and US existing home sales for August 2026.
On the earnings front, Citigroup, JPMorgan and Wells Fargo are all scheduled to report today.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 13 October 2026 - 8:23 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.