Markets Shift Into High Gear: Tesla and Meta Earnings Follow SpaceX Buzz; Sentiment Remains Neutral
The trading week is gathering momentum, with major market movers emerging from both the macroeconomic front and the corporate earnings season. Overall sentiment remains broadly neutral, as investors continue to balance concerns over inflation and the cost of money against the mostly positive news coming from quarterly earnings reports. Today, the spotlight is on Tesla (with Musk looking to repeat his success following SpaceX’s strong performance), Meta (bringing the focus back to revenue generation and the sustainability of its investments), and IBM.
On the macroeconomic front, UK inflation figures, combined with stronger-than-expected labour market data, appear to pave the way for a Bank of England rate hike at its November meeting. The GBP/USD exchange rate has risen to a score of 56, its highest level since last August. Futures point to a positive opening for both European and US markets.
Market Weather Map
October 21, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
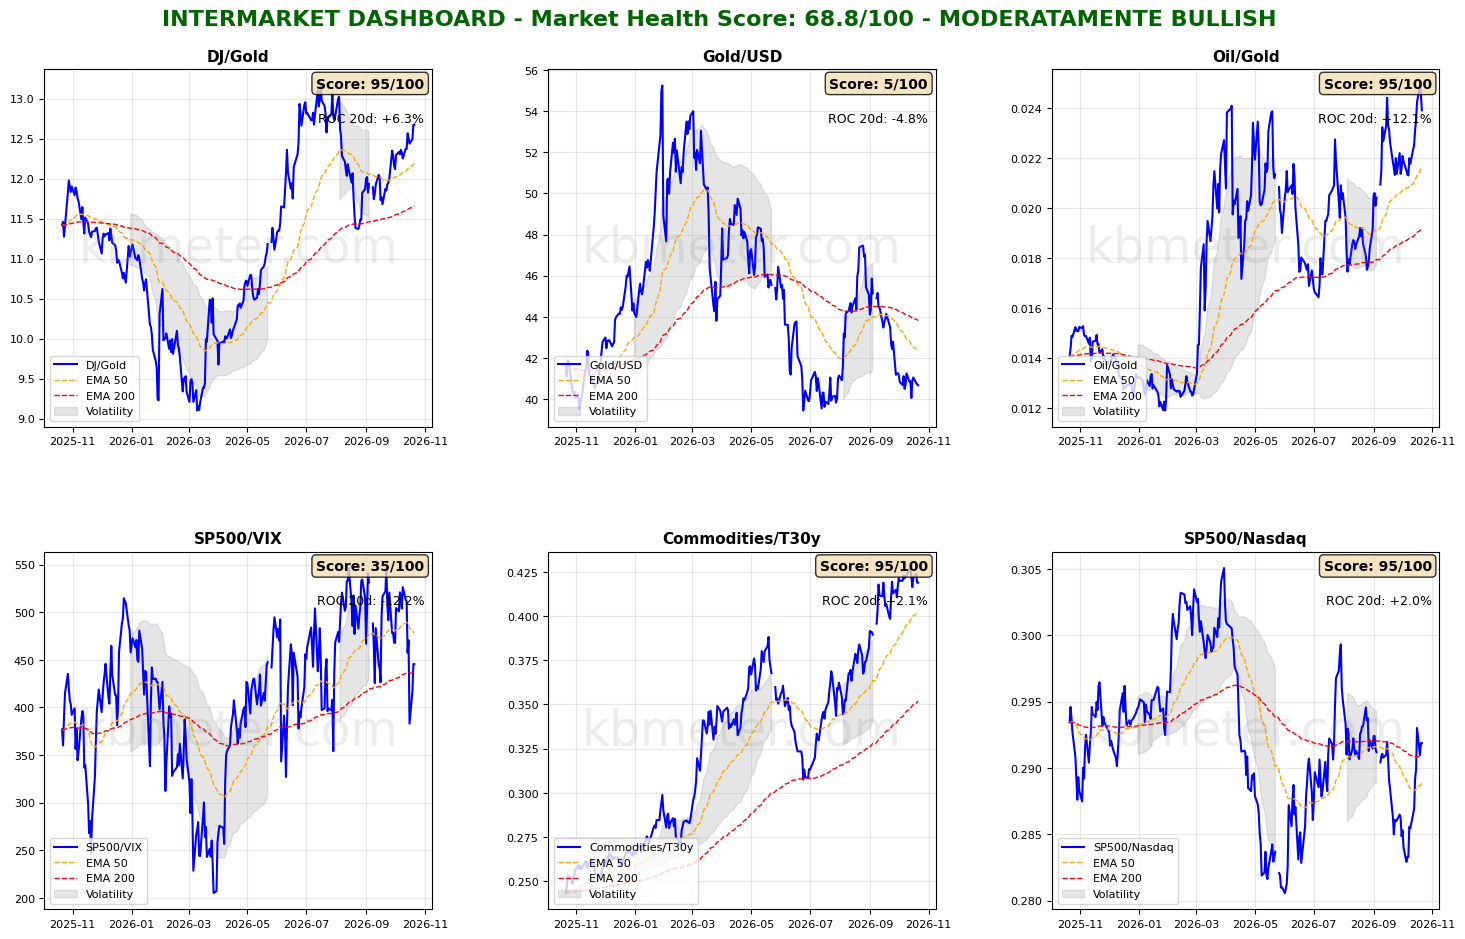
Financial markets are showing a neutral sentiment today. Intermarket analysis indicates a Market Health Score of 69/100.
Two developments stand out in our intermarket dashboards. The S&P 500/VIX ratio has moved back above its long-term moving average, while the S&P 500/Nasdaq ratio has held above its long-term moving average and remains at its highest levels since early September.
Gold is weakening again, losing ground relative to both the US dollar and oil. The Dow/Gold ratio has recovered to levels last seen in July. While this move is certainly influenced by the weakness in bullion, the US equity index is also reaching a score of 64.
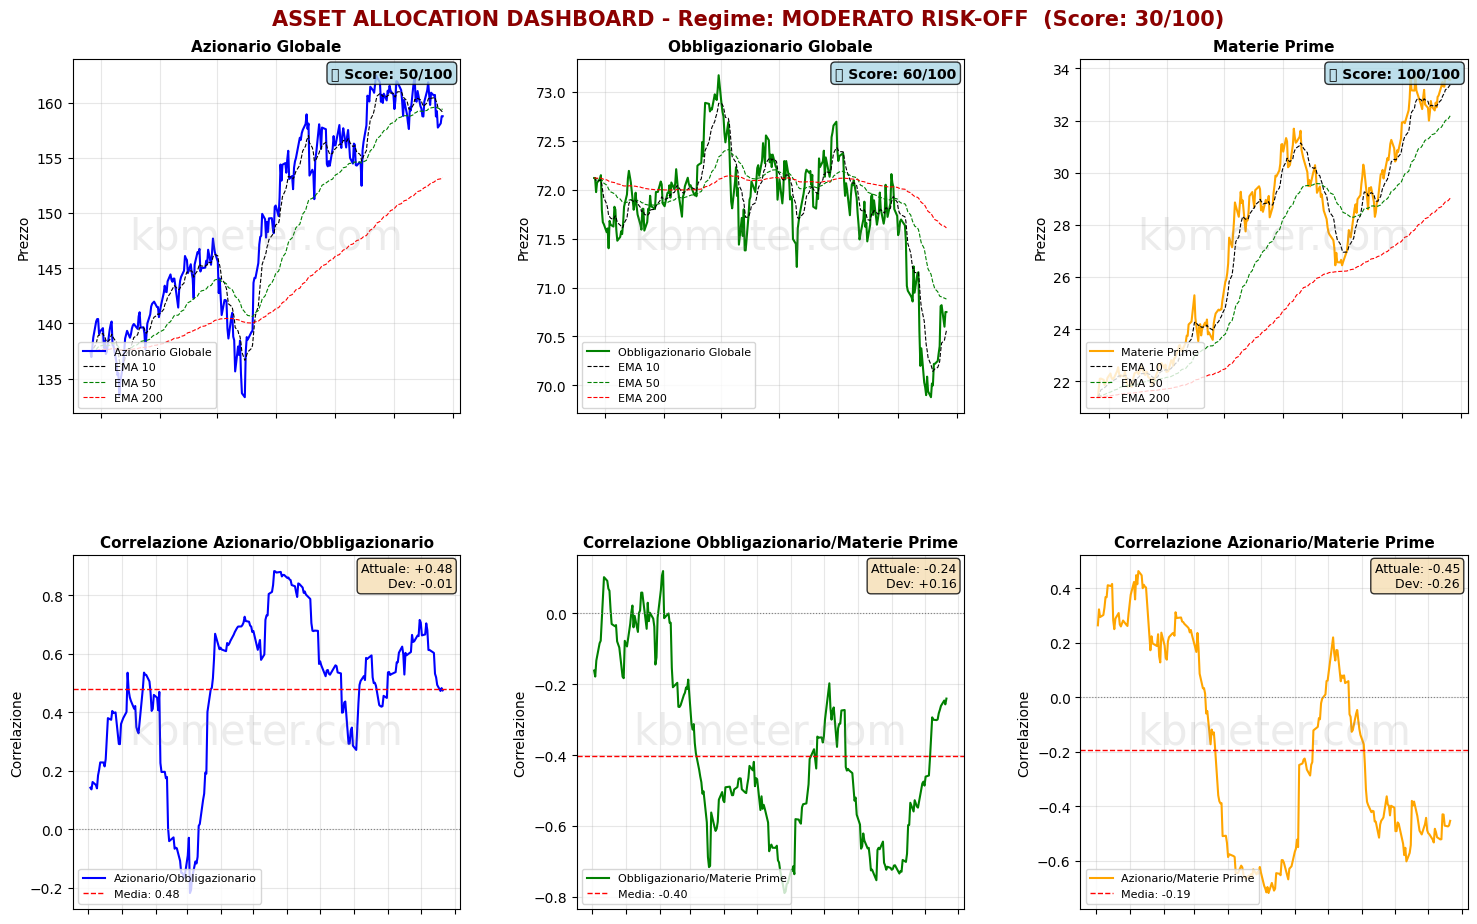
Across asset classes, the overall picture remains broadly stable. Global equities continue to trade sideways in the short term, global bonds remain within the channel defined by the inverted short- and medium-term moving averages, and commodities remain near their period highs.
Turning to our market weather map, the US dollar and oil continue to rank among the highest-scoring assets, while the S&P 500 technology sector appears to have stabilised just below the neutral threshold of 50 points.
The broader picture still points to widespread neutrality. The average score across the more than 100 assets we monitor remains stable at around 50 points, with 37% of assets scoring between 45 and 55.
A review of daily and weekly changes highlights significant activity across commodities. Precious metals are weakening and copper is losing momentum, while some agricultural commodities—coffee in particular—are showing strength, in contrast with the weakness affecting many grains.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures point to a moderately risk-on sentiment, with an average change of +0.12%. The US is slightly positive (+0.26%), Europe is also slightly positive (+0.36%), while Asia is in negative territory (-0.98%).
📊 Global Futures – Pre-Market Sentiment
- Taiwan: +1.23%
- IBEX 35: +1.21%
- US Tech 100: +0.71%
- CSI 300: -1.18%
- Hang Seng: -0.89%
- Nikkei 225: -0.86%
Macroeconomic calendar
The macroeconomic agenda centres on Japanese export data and UK inflation figures. Also worth monitoring are Indonesia’s monetary policy decisions, movements in US 30-year mortgage rates, and remarks from Bundesbank President Joachim Nagel.
As for corporate earnings, today is all about Meta, Tesla and IBM.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 21 October 2026 - 8:36 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.