Gold, Oil and Tech in Focus After Midterms; Market Sentiment Remains Neutral Ahead of BoE Decision
Gold, oil and the US technology sector remain the key players in financial markets in the aftermath of the US midterm elections. They are also the main indicators for understanding how investors are interpreting the election outcome. Gold is benefiting from the weakness in oil and the US dollar, while the tech sector remains under pressure amid concerns over a potentially less business-friendly regulatory environment. European equities are the main beneficiaries of this environment, while the commodities sector continues to lose momentum.
Meanwhile, markets are awaiting the Bank of England’s decision, with investors expecting an interest rate hike. Sentiment remains neutral, while futures point to a positive opening for European markets and a negative start for US equities.
Market Weather Map
November 5, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
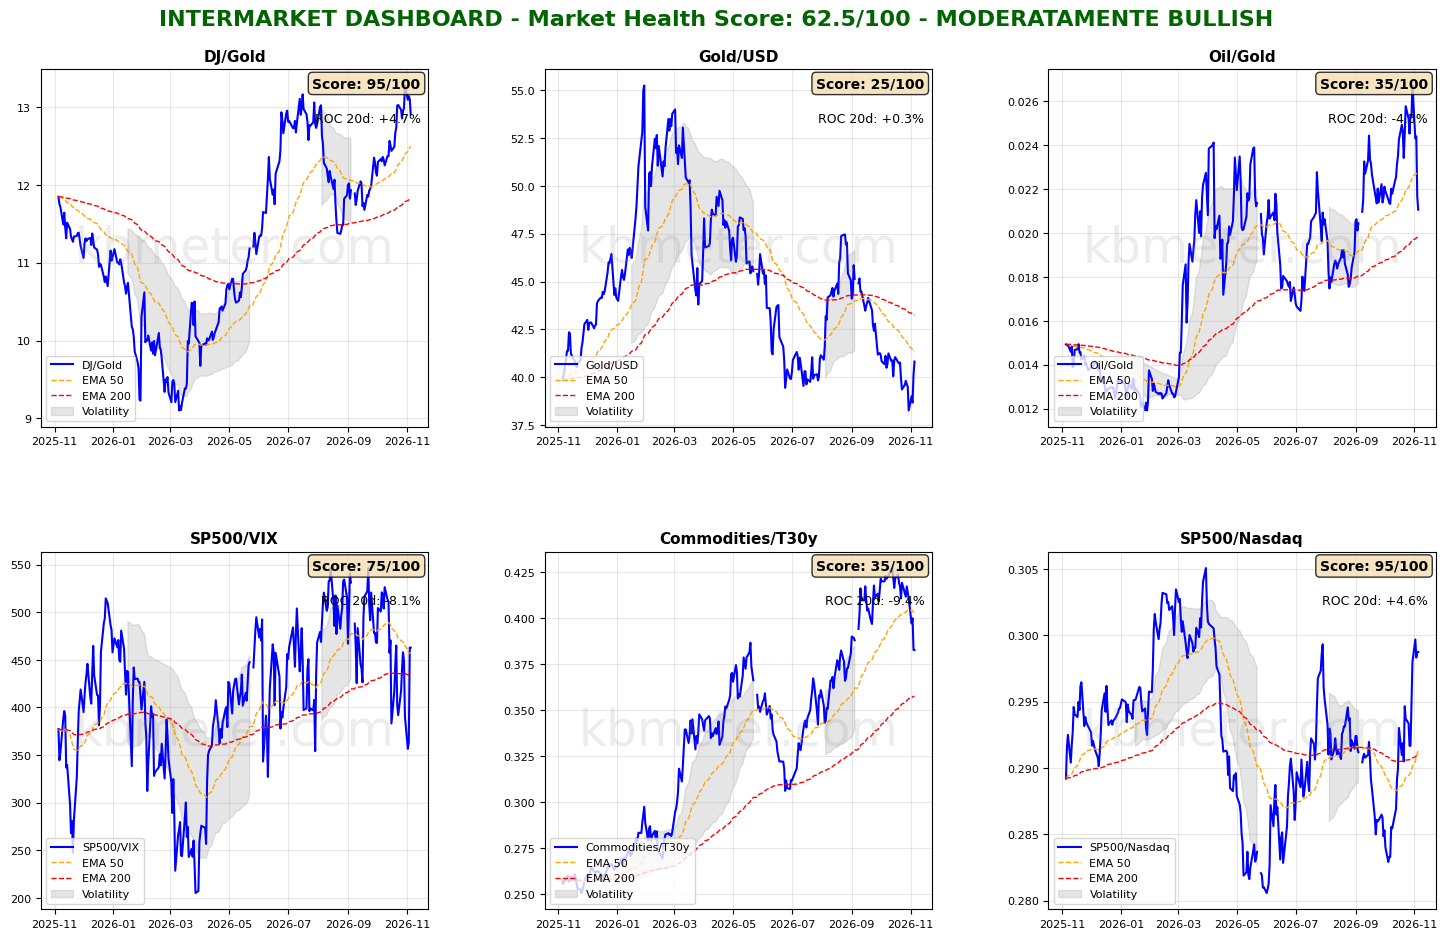
Financial markets are currently showing neutral sentiment. Intermarket analysis points to a Market Health Score of 62/100.
Two developments stand out in our intermarket dashboards. The first is the continued recovery in gold immediately following the midterm elections, supported by the simultaneous decline in the US dollar and oil prices. The Dow/Gold ratio is retreating from its recent highs, while the Oil/Gold ratio has broken below its medium-term moving average.
The sharp drop in oil prices, coupled with a recovery in US Treasuries, has pushed the Commodities/Bonds ratio below its medium-term moving average and down to its lowest levels since last September. The S&P 500/VIX ratio has moved back above its long-term moving average, while the S&P 500/Nasdaq ratio has remained relatively unchanged.
The overall picture across asset classes remains broadly unchanged compared with our previous analyses, although some trends are becoming more pronounced.
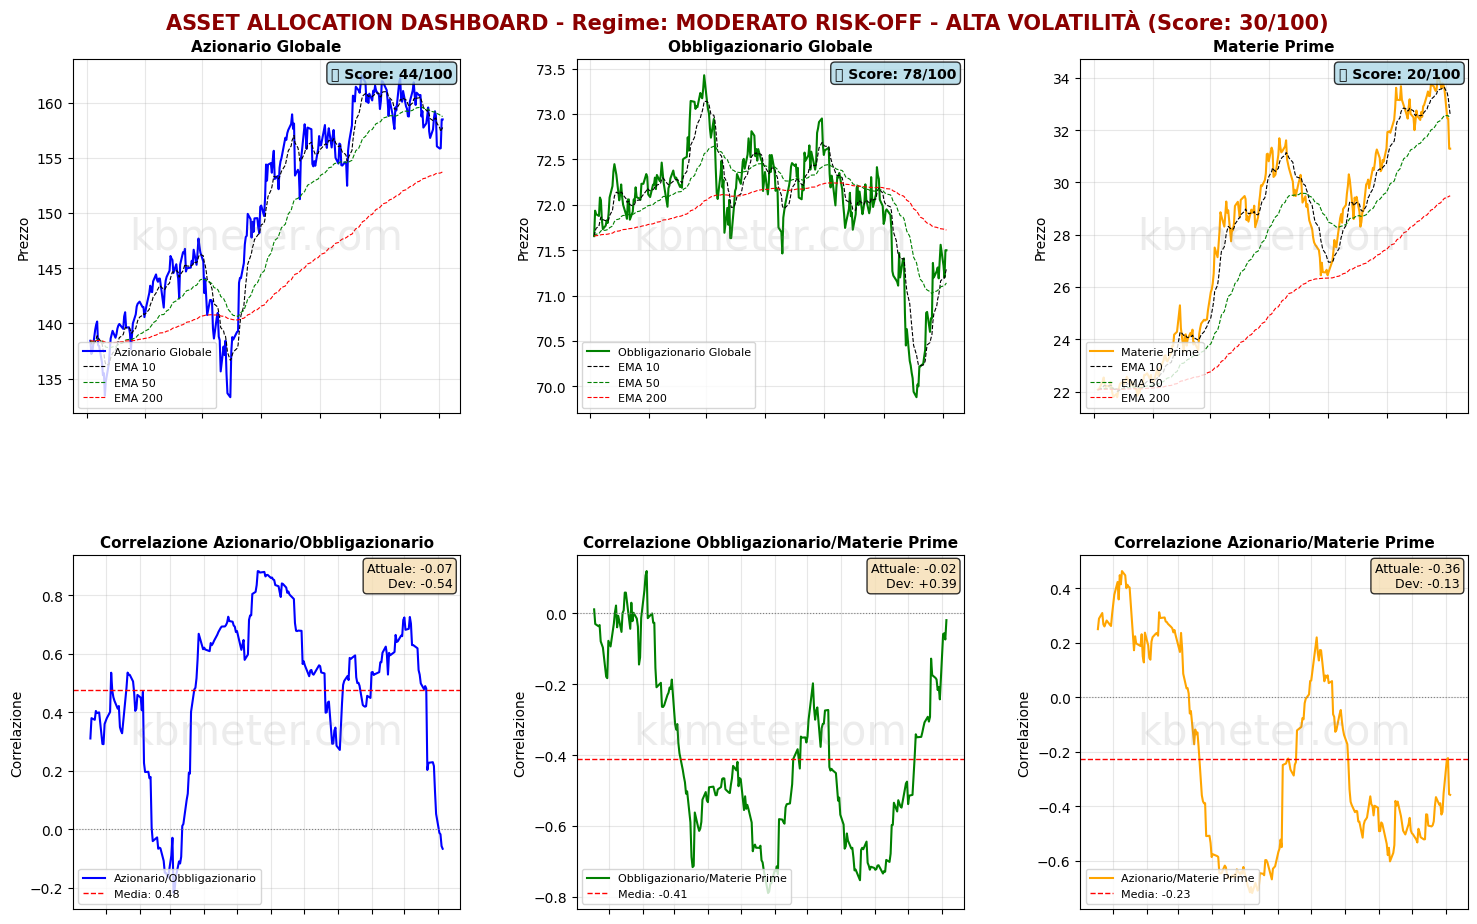
Commodities continue to lose momentum amid the significant decline in oil prices, while bonds are attempting to approach their long-term moving average. A decisive break above this level would confirm a trend reversal compared with the performance seen over recent months.
Global equities remain in limbo, trading below their medium-term moving average. We continue to view the current short-term trend as broadly sideways
Our Market Weather Map confirms that equities remain in neutral territory, although Europe has climbed to a score of 58.
The S&P 500 Technology sector remains below the 50-point threshold, while the scores are also beginning to signal early signs of recovery in gold. The US dollar is slipping towards the 50-point mark, while cryptocurrencies and commodities remain below this threshold.
Global Futures – Pre-Market Sentiment
Global futures are signalling a moderately risk-on sentiment (+0.20% on average), with US futures slightly negative (-0.36%), European futures strongly positive (+1.56%) and Asian futures in negative territory (-0.90%).
📊 Global Futures – Pre-Market Sentiment
- IBEX 35: +3.68%
- FTSE MIB: +2.75%
- CAC 40: +2.52%
- Taiwan: -4.11%
- Nikkei 225: -3.27%
- US Tech 100: -1.32%
Macroeconomic calendar
On the macroeconomic front, today’s agenda includes the release of German industrial orders for September 2026 and updated industrial production figures from France. This afternoon, US data will provide updates on job cuts and initial jobless claims. As far as monetary policy is concerned, today is the Bank of England’s turn, with markets expecting an interest rate hike.
On the corporate earnings front, investors will be focusing on quarterly results from Toyota, Airbnb, Deutsche Telekom, DBS and ConocoPhillips.
Assets to watch
Data as of Nov 4, 2026We have split the KBMeter scores into three bands, depending on their value: Weak, Intermediate or Strong. Here you can see which bands are most at risk of changing over the next 5 days and which ones hold.
The number on the right is the share of similar past cases in which the band had changed after 5 days. The higher it is, the more likely it is to change. The arrow in the current band appears when the asset is close to the border with the neighbouring band.
CONTINUE READING. ACTIVATE YOUR 14-DAY FREE TRIAL NOW. CLICK HERE
Already a subscriber? Login here
It does not say whether the price will rise or fall and it is not investment advice.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 5 November 2026 - 8:29 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.