Financial Markets Hold in Neutral Territory Ahead of Micron Earnings and US Jobs Data
The week in the financial markets begins with sentiment still broadly in neutral territory. On the one hand, pressure on bond yields, also driven by renewed expectations of higher interest rates; on the other, equities continue to hold up thanks to the technology sector and macroeconomic data that continue to point to a resilient global economy. The coming days could either confirm or challenge the current scenario. On Wednesday, the first major earnings release for the technology sector is due from Micron, while on Friday investors will receive the latest figures on US employment in September, along with the latest inflation data for the Euro area. In the meantime, gold continues to struggle, losing ground against the US dollar and falling below a score of 40 on our Market Weather Map. Futures point to a negative opening in the US and a slightly positive start in Europe.
Market Weather Map
September 28, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
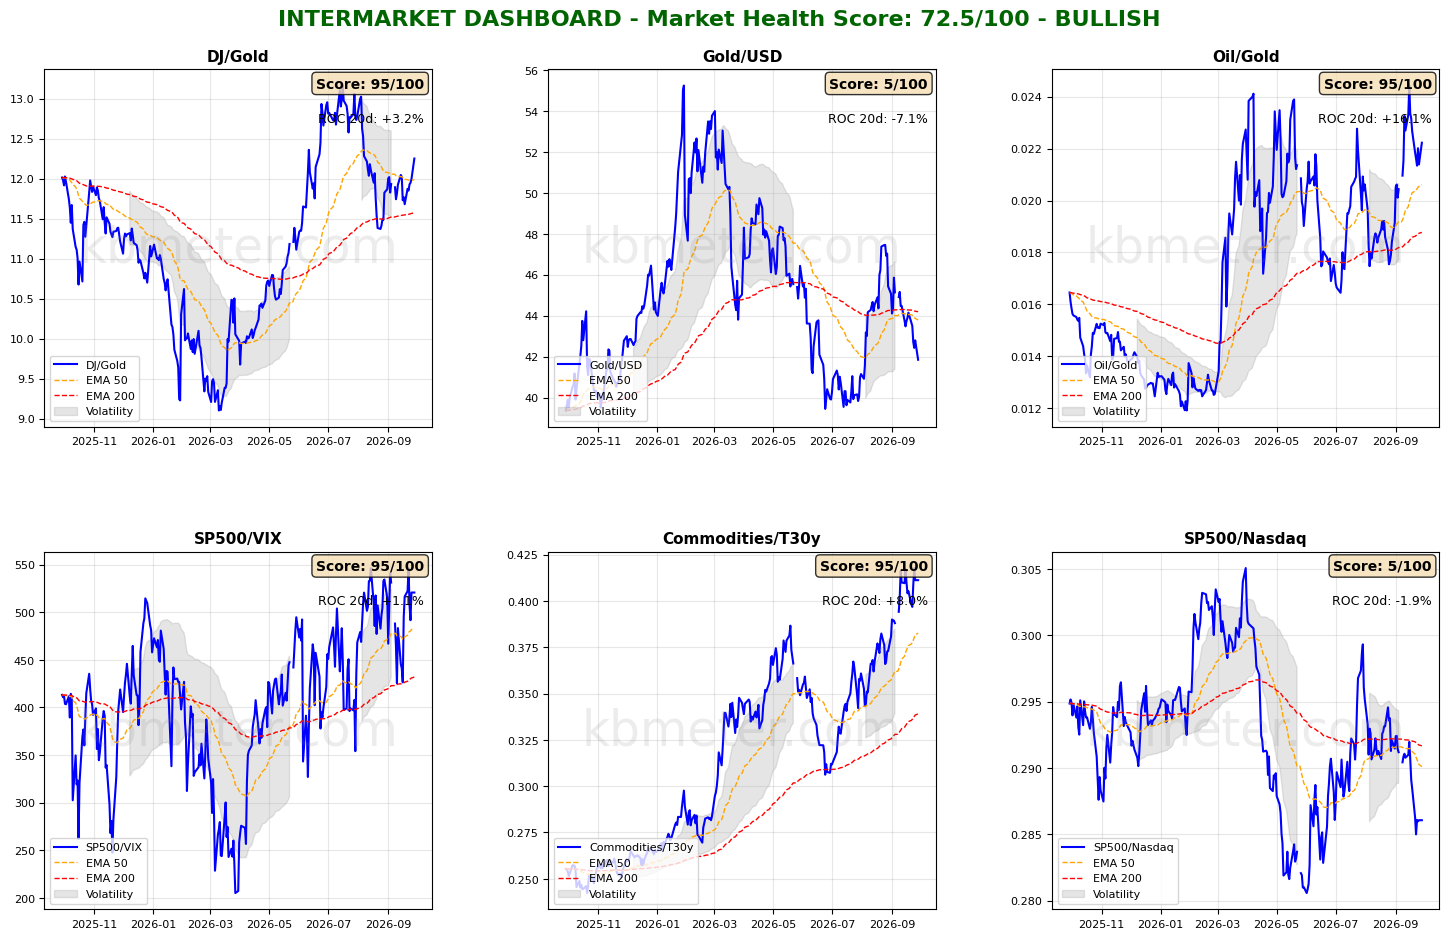
Financial markets are showing neutral sentiment today. Our intermarket analysis indicates a Market Health Score of 72/100. Two factors continue to characterize the current phase in financial markets. On the one hand, there is persistent pressure on bond yields; on the other, equities remain resilient, supported by macroeconomic data and the technology sector. This week will likely put both factors to the test. In the meantime, the intermarket dashboards continue to confirm the overall picture. Gold remains weak amid expectations of tighter monetary policy and a strong US dollar. The Gold/USD ratio is back near its lowest levels since last July, while the Dow/Gold ratio is accelerating again above its medium-term moving average. The Oil/Gold ratio remains in an upward trend, while the Commodities/Bonds ratio remains near its period highs. Overall, risk appetite remains positive.
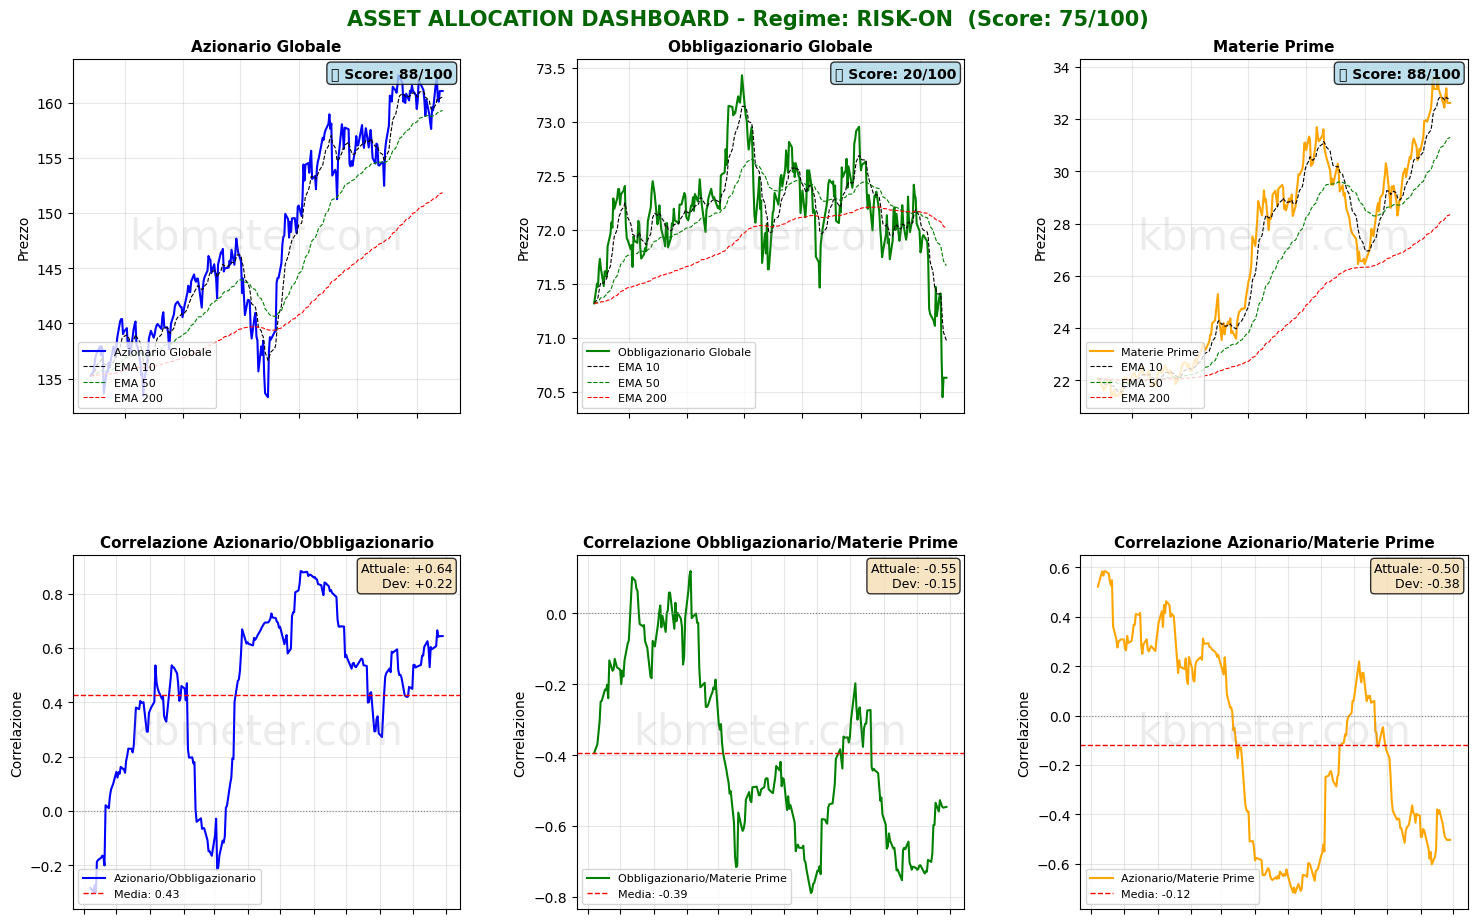
There have been very few changes across asset classes. Global bonds are attempting to find support, while global equities remain in a bullish configuration, although the upward move is showing limited momentum. Commodities remain near their period highs.
Our Market Weather Map confirms a moderately positive outlook for the US dollar and cryptocurrencies, neutral conditions for equities—with Asia being the region most affected by the strength of the US dollar—and weakness in bonds and, above all, gold.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures are pointing to moderately risk-off sentiment (-0.18% on average), with the US slightly negative (-0.47%), Europe slightly positive (+0.23%), and Asia slightly negative (-0.47%).
📊 Global Futures – Pre-Market Sentiment
- Hang Seng: +0.73%
- FTSE MIB: +0.60%
- IBEX 35: +0.54%
- CSI 300: -1.71%
- Nifty 50: -0.88%
- US Tech 100: -0.66%
Macroeconomic calendar
The macroeconomic calendar starts the week with relatively few data releases. Key events to watch include the update on Indian industrial production for August and the minutes from the Bank of Japan’s September meeting.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 28 September 2026 - 7:26 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.
