Bonds Slide Again as Markets Hold Neutral Sentiment Ahead of Trump-Xi Meeting
Market sentiment remains in neutral territory, with signs of risk-on positioning in equities offset by renewed tensions in bond yields. Better-than-expected PMI surveys are fueling expectations of higher interest rates, weighing not only on global fixed income but also on gold, which has fallen below a score of 40 and now stands just under five points above its one-year low. On the geopolitical front, the focus is on the meeting between Trump and Xi, while the prospect of renewed talks between the United States and the Middle East is becoming increasingly uncertain. Oil remains in neutral territory according to our Health Scores. Futures point to a below-par opening in the United States and a negative opening in Europe.
Market Weather Map
September 24, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
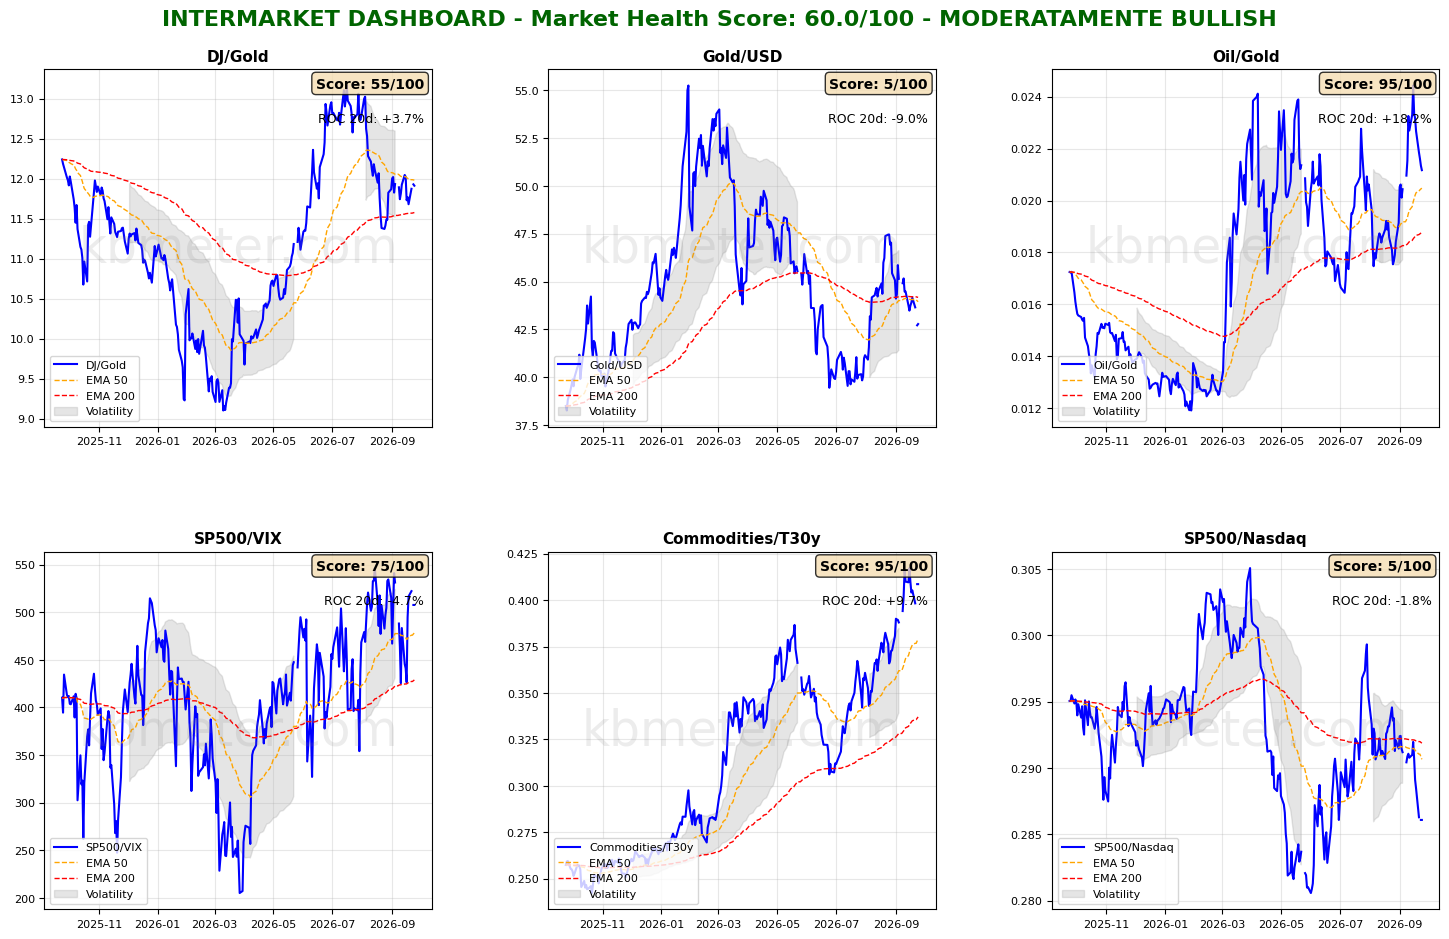
Financial markets are showing neutral sentiment today. Our intermarket analysis indicates a Market Health Score of 60/100. Commodities and yields continue to drive the dynamics across our intermarket dashboards. While risk appetite indicators remain broadly stable, yesterday saw the decline in the oil/gold ratio come to a halt, alongside a rebound in the commodities-to-bonds ratio. A direct consequence of expectations for tighter monetary policy is the loss of momentum in gold relative to both the US dollar and the Dow.
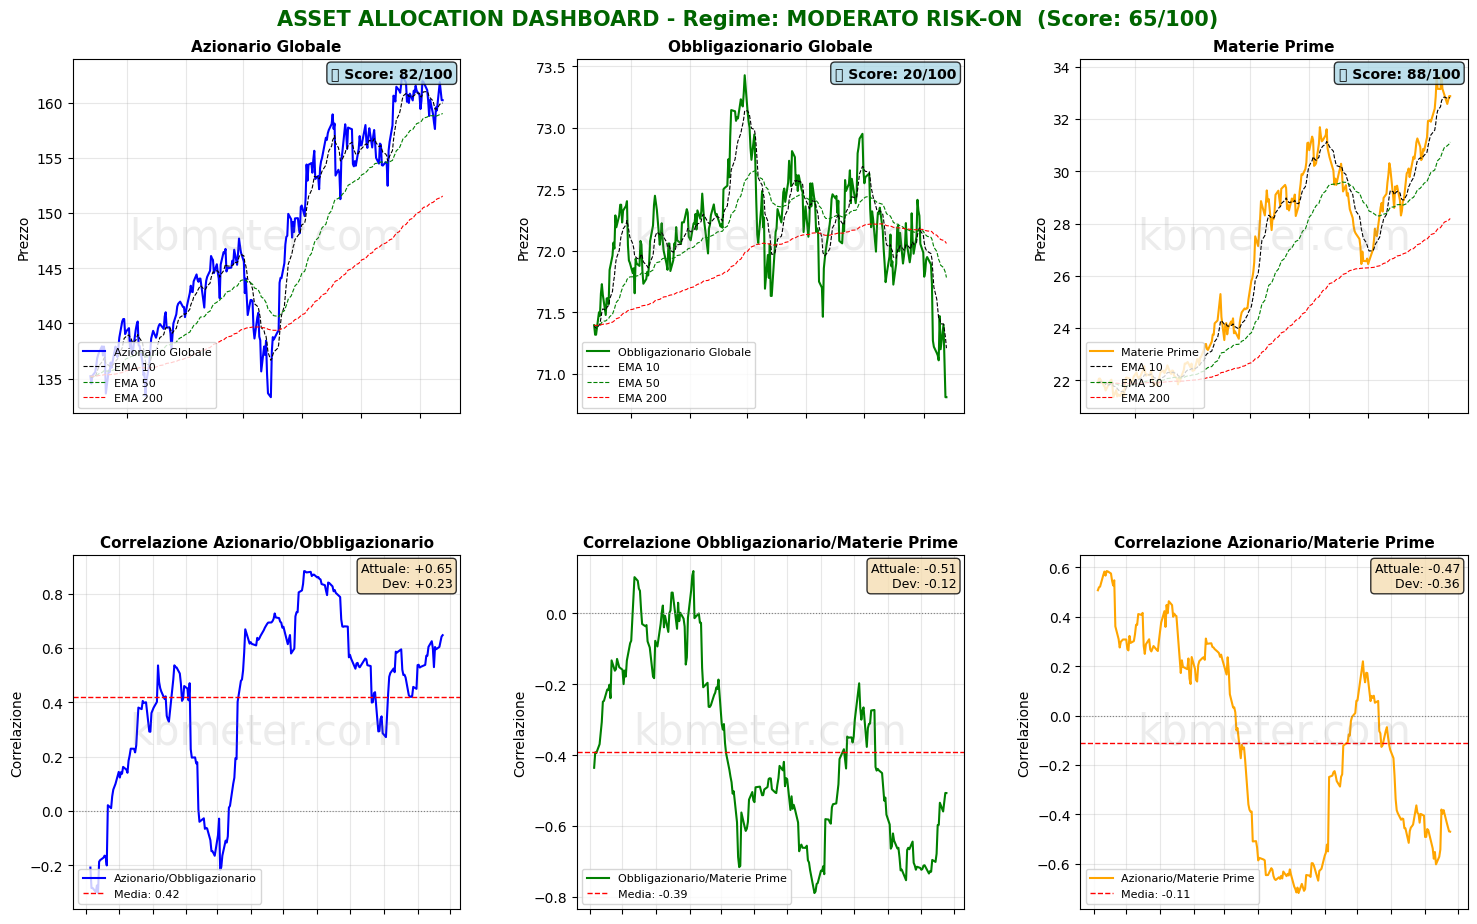
The picture becomes even clearer when looking at the performance of the individual asset classes. The rebound in global bonds has given way to a further loss of ground, bringing the asset class back to new lows for the period. Global equities are losing momentum but remain above their short-term moving average, while commodities remain near their period highs.
Our weather map confirms neutral signals for equities—with Asia showing greater weakness—marked weakness in gold and bonds, and strength in the US dollar, the technology sector and cryptocurrencies, in no particular order.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures point to a moderately risk-off sentiment (-0.36% on average), with the US slightly negative (-0.19%), Europe negative (-0.55%), and Asia slightly negative (-0.02%).
📊 Global Futures – Pre-Market Sentiment
- CSI 300: +0.41%
- Hang Seng: -0.02%
- FTSE 100: -0.05%
- IBEX 35: -1.28%
- FTSE MIB: -0.99%
- Nifty 50: -0.94%
Macroeconomic calendar
On the macro front, today’s agenda includes the September 2026 PMI survey data for Japan, developments in the Australian labor market, an update on the German business confidence index, and US figures on new home sales and unemployment benefits.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 24 September 2026 - 8:15 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.
