Bond Yields Keep Markets on Edge as Stocks Lean on Tech and Hopes for US-Iran Talks; Sentiment Remains Neutral
The period of tension in bond yields continues. Yesterday’s surge briefly pushed the yield on the U.S. 10-year Treasury close to 5.14%, a level not seen since 2007. But it is the entire fixed-income market that is sending signals of elevated inflation expectations — and not only that. Among analysts, a question is now beginning to emerge: how long can equities withstand this kind of pressure?
For the time being, our scores point to a neutral market environment, with the technology sector still in positive territory and the latest developments in the Middle East reopening the possibility of a resumption of negotiations between the U.S. and Iran. Certainly, the October earnings season could prove to be a potential turning point. In the meantime, futures are pointing to a flat opening in the U.S. and a slightly positive start in Europe.
Market Weather Map
September 25, 2026
US Equities
Eu Equities
Asia Equities
Commodities
Bonds
Dollar Index
Technology
Gold
Oil
Crypto
Market Summary
Do you want to see the score details for all assets monitored by KBMeter?
Try free for 14 days →Financial markets sentiment
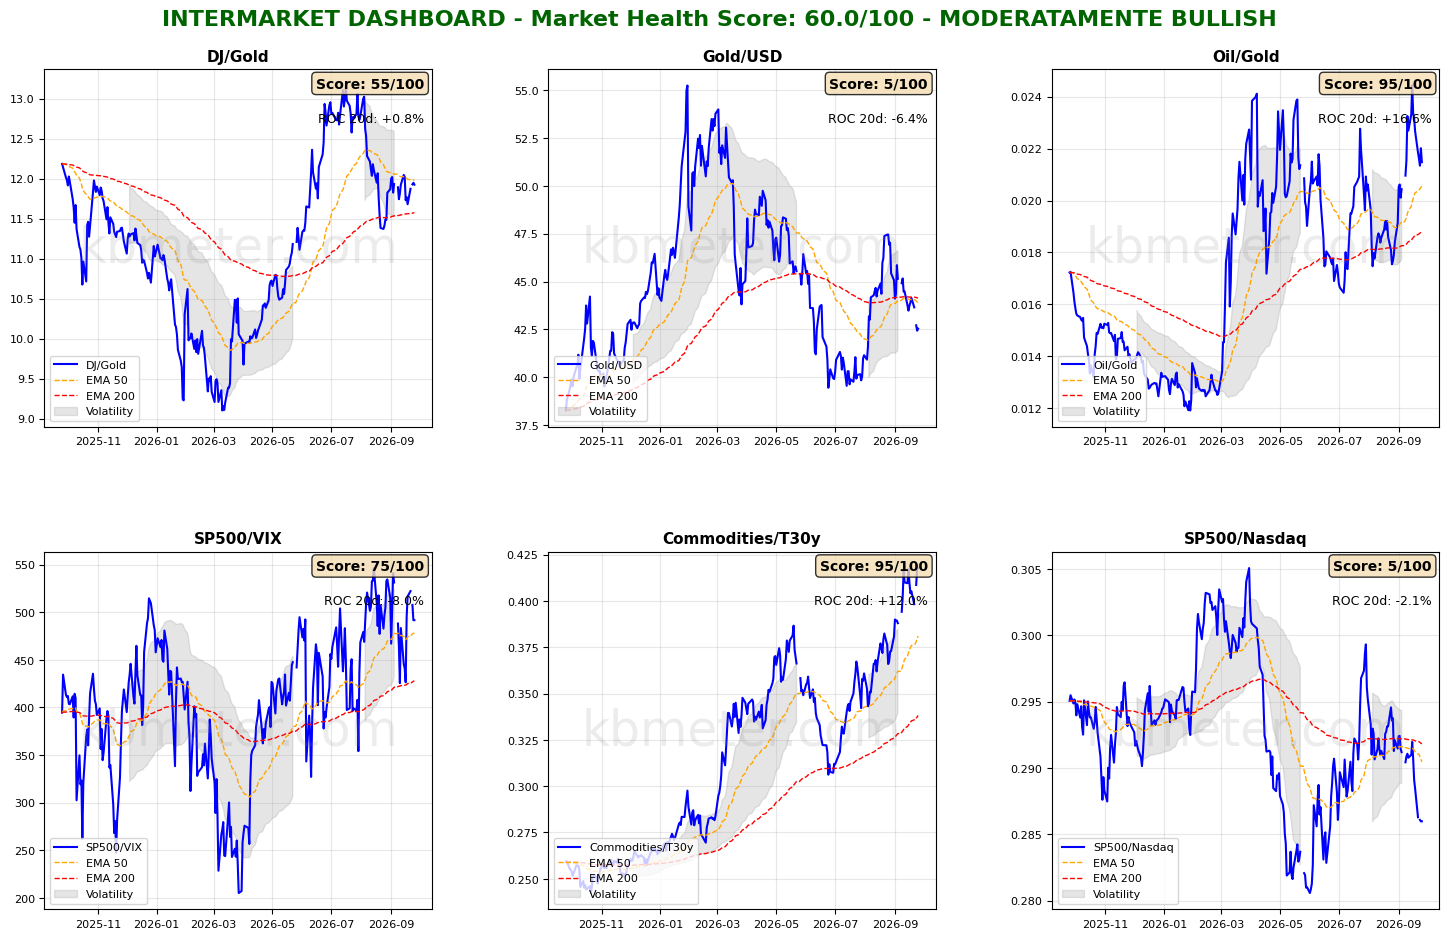
Financial markets are showing a neutral sentiment today. Intermarket analysis highlights a Market Health Score of 60/100. Within our intermarket dashboards, the most interesting ratio to monitor remains the relationship between commodities and bonds. With bond yields continuing to rise, the ratio is returning to period highs, also supported by oil prices, which remain stable.
Despite this, the main risk-appetite indicators remain positively oriented, with the S&P 500/VIX ratio above its medium-term moving average and the S&P 500/Nasdaq ratio holding at levels last seen at the beginning of last summer.
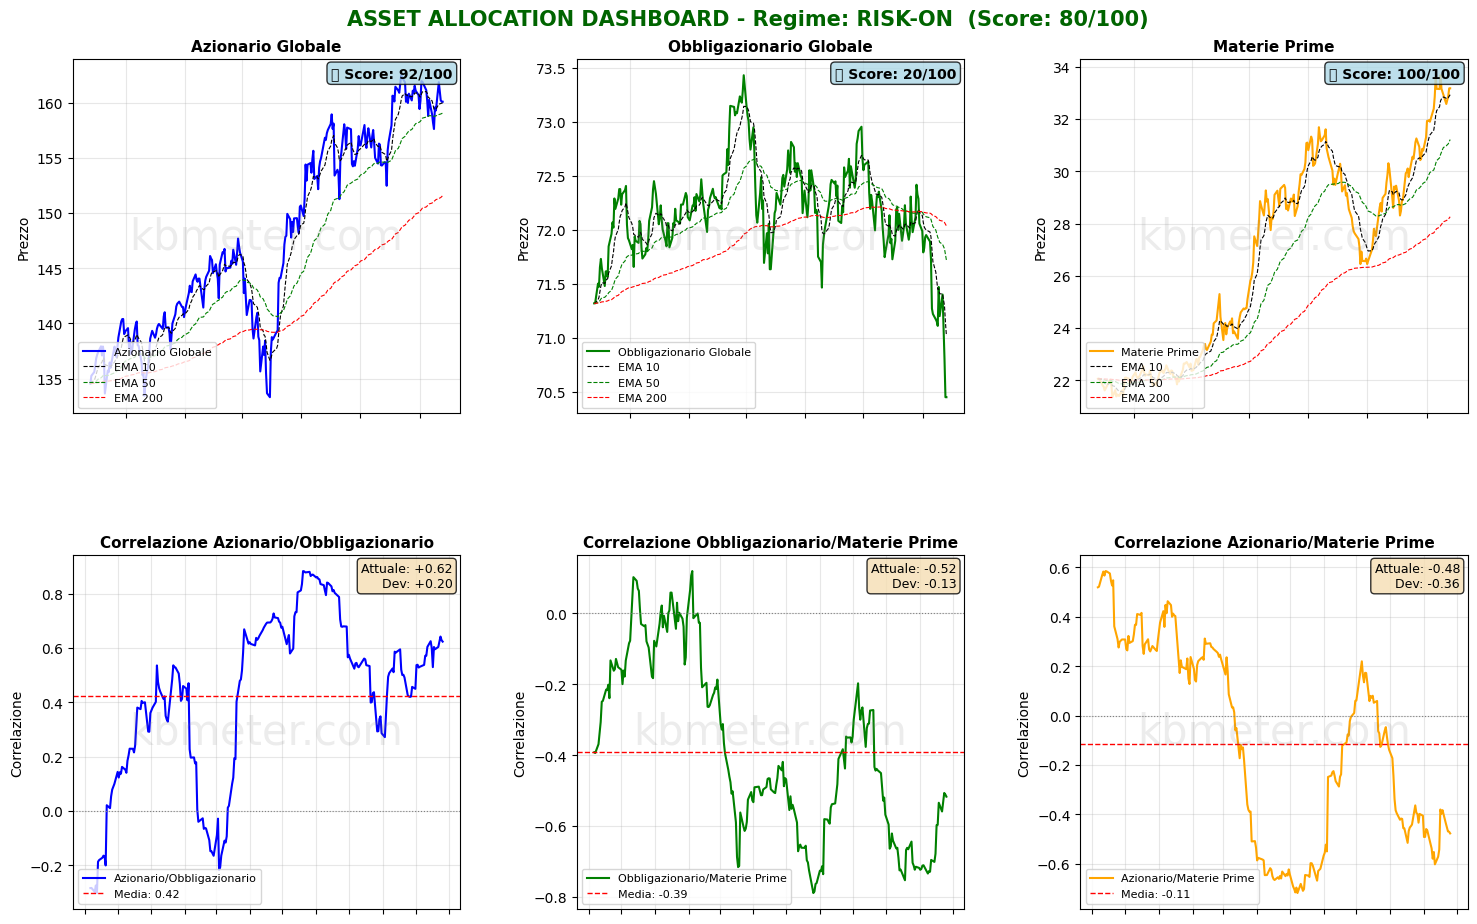
There have been few changes across asset classes, with equities remaining above their key moving averages, albeit with some signs of slowing momentum, while fixed income remains near the lows of the period.
Our market weather map confirms a neutral assessment for equities, with the technology sector remaining more than 10 score points above North American equities. Bonds and gold are being weighed down by the surge in yields, while the U.S. dollar is strengthening on expectations of further Fed rate hikes. Cryptocurrencies are also worth monitoring, as they have moved back above the 65-point threshold.
Global Futures – Pre-Market Sentiment
Pre-Market Futures: Global futures are signaling a moderately risk-off sentiment (-0.01% on average), with the U.S. slightly positive (+0.03%), Europe slightly positive (+0.17%), and Asia negative (-0.63%).
📊 Global Futures – Pre-Market Sentiment
- Nikkei 225: +1.02%
- Euro Stoxx 50: +0.59%
- IBEX 35: +0.57%
- CSI 300: -1.71%
- Hang Seng: -1.20%
- FTSE MIB: -0.84%
Macroeconomic calendar
On the macroeconomic front, today’s agenda includes German consumer confidence data, private-sector credit developments in the euro area, U.S. durable goods orders for August, and the final September reading of the University of Michigan consumer sentiment index.
Already a subscriber? Login here
NOTES AND WARNINGS
Data compiled by kbmeter.com. Analysis date: 25 September 2026 - 8:29 AM GMT+1
This content is provided for informational purposes only and should not be considered financial advice. All scores and assessments are based on the previous trading day’s closing prices. Futures indications refer to the date and time of the analysis.
